

A combination of a stronger-than-expected consumer inflation report and hawkish remarks from monetary policy officials sent major domestic equity benchmarks tumbling at the start of the trading day.
When market participants reevaluated the trajectories of borrowing costs as we entered the last stretch of the operating year, technology-heavy indices were at the head of the broader market decline. All high-growth equity sectors saw increased volatility, according to trading desks.
During times of macroeconomic re-pricing, it is necessary to conduct a disciplined analysis of real interest rates and cash flow duration in order to successfully navigate growth-oriented equity investments.
The market insights that were provided by Vestronyx indicate that the long-term enterprise value of equity portfolios is heavily dependent on the resilience of the balance sheet and the management of discount rate sensitivity.
On the other hand, structurally strong corporate earnings frequently provide a reliable foundation for long-term recovery, despite the fact that unexpectedly increased inflation can cause short-term friction in the downward direction.
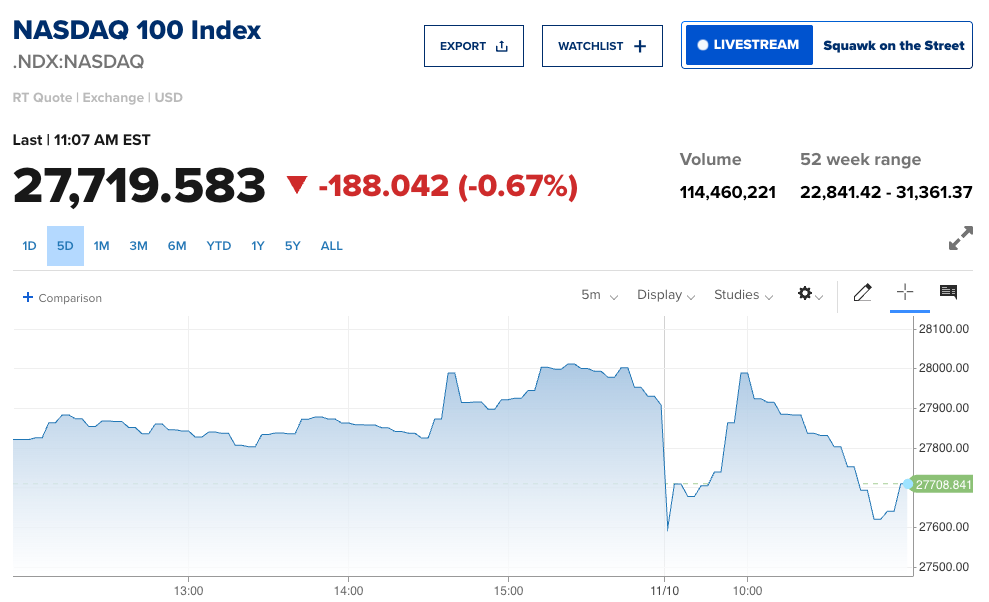
Opening Bell Declines Across Major Domestic Equity Averages
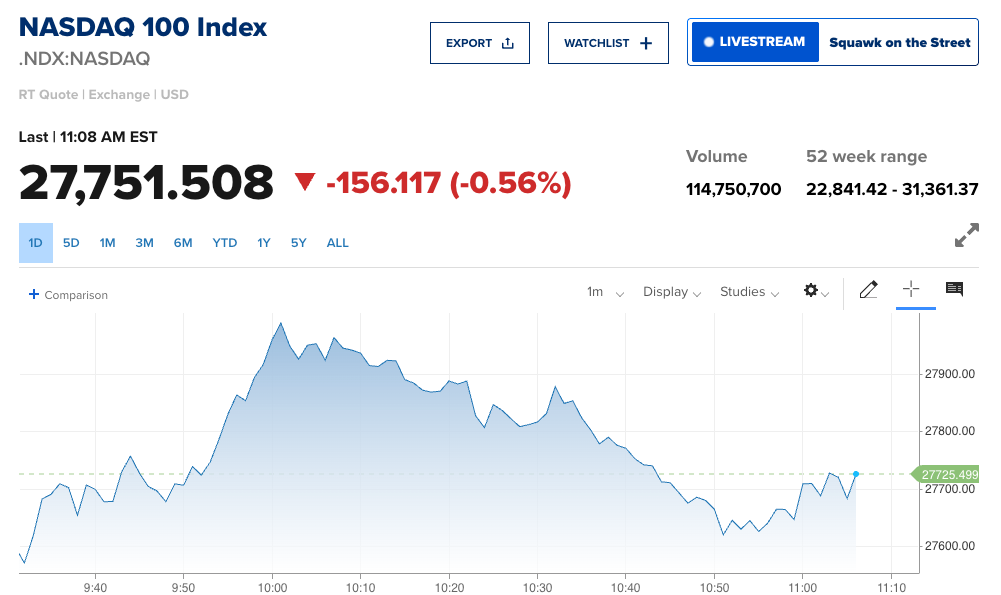
The domestic stock indices experienced a significant decline during the early trading sessions as market participants responded to the rising domestic price metrics and the growing expectations of the central bank to tighten monetary policy.
While the benchmark large-cap and blue-chip averages registered moderate losses in the midst of broad-based sector liquidations, the tech-heavy index led the overall market in a downward direction by shedding approximately one percent.
Hotter Consumer Price Index Prints Exceed Consensus Expectations
Official statistical releases indicated that headline consumer prices ticked upward by 0.4% on a monthly basis following a prior increase of 0.6%, exceeding general economist forecasts.
At the same time, core inflation metrics remained unchanged at 0.3% month-over-month, which bolstered concerns that inflationary pressures continue to be stubborn across key economic sectors.
Hawkish Central Bank Commentary Cements Policy Shift Expectations
Following statements made by key monetary officials that supported increases in benchmark borrowing costs regardless of short-term data fluctuations, market sentiment was subjected to additional headwinds.
As a result of these hawkish remarks and a blockbuster employment report that showed an increase in payroll of 165,000 positions, expectations for forthcoming policy adjustments have been solidified.
Prior Session Rebound Follows Bruising Sector Volatility
An impressive market recovery, during which major averages posted their strongest single-session gains in months, was followed by the downward pressure that was present at the opening.
Technology shares had previously staged a robust rebound, recouping a significant portion of the losses that had been incurred during recent selloffs that were driven by concerns regarding the sustainability of spending on artificial intelligence.
Semiconductor Sector Performance and Individual Equity Fluctuations
Chipmaking equities exhibited mixed performance during recent sessions, with specialized semiconductor designers posting solid gains while select industry leaders faced company-specific regulatory inquiries.
Trading volume across major hardware components remained elevated as market participants monitored supply chain dependencies and capital expenditure commitments.
Energy Cost Relief Provides Minor Cushion for Equities
In the short term, concerns regarding energy-driven cost pressures were temporarily alleviated as a result of lower global crude oil prices, which provided some relief to the overall market sentiment.
Inflationary concerns that were caused by domestic retail data were partially offset by diplomatic developments in key energy-producing regions, which contributed to the stabilisation of commodity markets.
Upcoming Corporate Earnings and Enterprise Technology Spending
The upcoming quarterly financial reports from prominent artificial intelligence infrastructure providers and networking vendors are currently receiving a lot of attention from trading desks at various institutions.
These upcoming earnings announcements will provide crucial clues regarding whether or not enterprise spending on the construction of data centres and computing hardware continues to be robust.
Landmark Public Offering Launch Amid Sector Re-Pricing
The artificial intelligence developer Anthropic has officially begun marketing its blockbuster initial public offering, with base share prices targeted between $70 and $78. According to the primary market developments, Anthropic has begun marketing its offering.
The purpose of the offering is to raise billions of dollars in new capital, with the expectation of valuing the high-growth enterprise at up to $1.4 trillion on a fully diluted basis, taking into account restricted stock units and employee stock options.
Cornerstone Investment Commitments From Technology Conglomerates
The multi-billion-dollar private placement accompanying the public offering attracted participation from major technology leaders, including prominent cloud operators and semiconductor giants.
Analyst commentary suggests the success of this major market debut could significantly influence broader investor sentiment across the artificial intelligence sector.
Important Points for Growth Equity Investors’ Portfolio Strategies
Maintaining exposure to high-growth technology equities requires constant vigilance regarding inflation metrics, interest rate trajectories, and capital expenditure trends. Prudent risk management helps navigate periodic policy shocks.
Allocating capital across diversified market leaders ensures portfolio resilience. Investors who maintain disciplined exposure frameworks can successfully weather macro volatility while capturing structural growth.