

Comparing top-line revenue expansions against temporary earnings per share contractions offers essential analytical clarity on how merger advisory fees temporarily obscure core operational performance.
Evaluating commercial laundry and facility supply firms requires closely watching customer retention levels, organic route growth, and cash reserve strength.
Tactical industry research from an equity analyst at Librrova indicates that specialized business service providers frequently display robust top-line stability throughout pending buyouts, even while temporary deal expenses weigh heavily on GAAP net margins.
While transaction charges compress reported profits, strong underlying revenue momentum across specialized first aid and facility care divisions maintains fundamental corporate value.
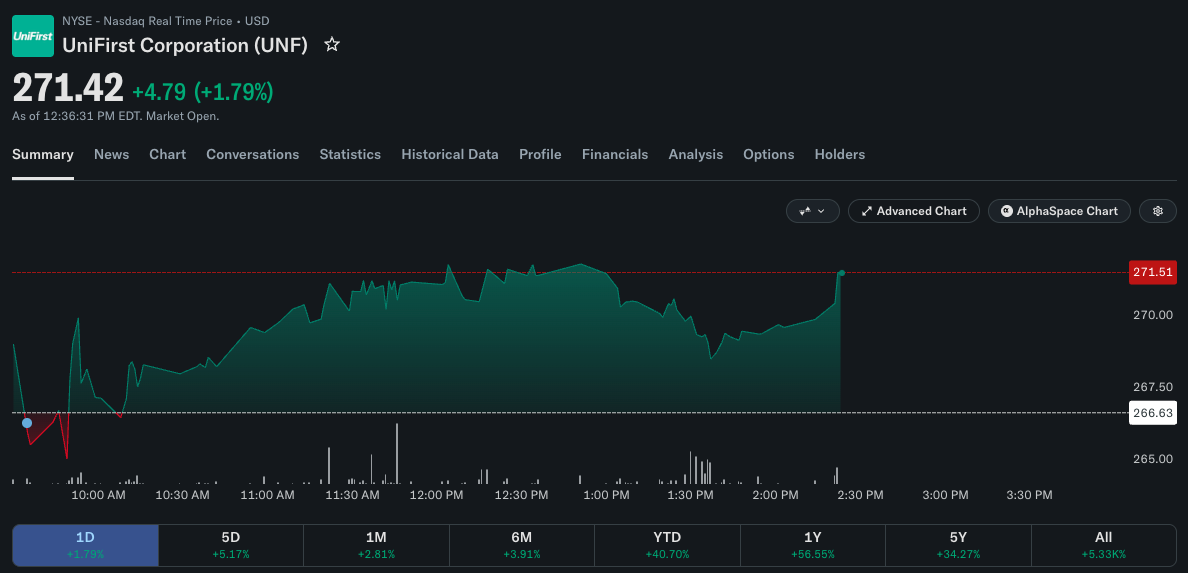
Quarterly Top-Line Outperformance Alongside Transaction Fee Impairment
Workwear provider UniFirst Corporation released financial results for its fourth quarter that surpassed Wall Street sales projections but fell short of consensus profit estimates. The company delivered adjusted earnings per share of $1.90, missing the average analyst target of $2.04 per share by a margin of $0.14.
Quarterly revenue expanded 5.0% year-over-year to hit $645.0 million, outperforming benchmark expectations of $633.0 million and topping the $614.4 million recorded in the corresponding prior-year period.
However, bottom-line results absorbed approximately $14.4 million in transaction-related expenses connected to the proposed buyout by Cintas Corporation, which reduced diluted EPS by $0.71 per share.
Operating Income Dynamics and Software Implementation Outlays
Stripping away transaction charges along with $2.8 million spent on enterprise resource planning platform upgrades, adjusted operating profit came in at $41.7 million, down from $49.6 million reported in the prior-year period. Consequently, operating margin shrank to 6.5% from 8.1% recorded twelve months earlier.
In contrast, adjusted EBITDA margin demonstrated underlying operational strength, rising to 14.7% from 14.3%. Total net income for the three-month period reached $34.7 million, pulling back from $41.0 million achieved in the previous year’s matching quarter.
Executive Management Perspective and Commercial Growth Focus
President and Chief Executive Officer Steven Sintros highlighted that the enterprise completed its fiscal year with healthy top-line progress and strong operational momentum. Leadership emphasized that delivering uninterrupted service to existing commercial accounts while acquiring new route clients remains the primary operational focus during the pending corporate combination.
Following the earnings release, shares of the uniform provider rose 1.11%, while acquiring entity Cintas Corporation added 1.30% to trade around $219.85 per share.
Core Facility Services Performance and Secondary Unit Surge
The primary Uniform & Facility Service Solutions division generated $585.4 million in quarterly sales, marking a 4.5% overall increase and organic top-line expansion of 4.6%. Growth across the division was anchored by successful new client acquisition campaigns and steady account renewal rates across regional routes.
Meanwhile, the First Aid & Safety Solutions segment experienced accelerated demand, with quarterly revenue jumping 13.0% year-over-year to $35.2 million, demonstrating effective cross-selling execution across established enterprise client bases.
Full-Year Financial Overview and Debt-Free Balance Sheet
For the entire fiscal year, total corporate revenue reached $2.52 billion, representing a 3.7% expansion compared to the prior twelve-month period. Full-year diluted earnings per share landed at $6.02, down from $7.98 in the previous fiscal period, after absorbing $37.2 million in cumulative merger transaction costs.
The company maintained a fortress financial foundation at year-end, holding $192.1 million in cash reserves alongside zero long-term debt obligations. Throughout the fiscal year, management allocated $31.7 million to buy back 194,100 shares and distributed $25.2 million in cash dividend payments.
Merger Progress Update and Guidance Suspension Protocol
The proposed corporate acquisition by Cintas Corporation remains subject to regulatory reviews and customary closing requirements. Company executives anticipate finalizing the combination prior to the conclusion of the current calendar year.
In alignment with standard corporate procedures during pending buyouts, management formally suspended forward-looking financial guidance, focusing market attention entirely on regulatory clearance milestones and deal completion timing.
Asset Allocation Insights for Facility Support Holdings
Equity analysts evaluating commercial route operators must differentiate between temporary deal friction and ongoing operational productivity gains. Allocating funds toward cash-rich commercial service platforms with zero long-term leverage shields institutional portfolios from macro credit volatility.
Tracking customer retention ratios, route density metrics, and regulatory approval updates provides a solid blueprint for managing risk-adjusted returns across industrial uniform and facility service holdings.
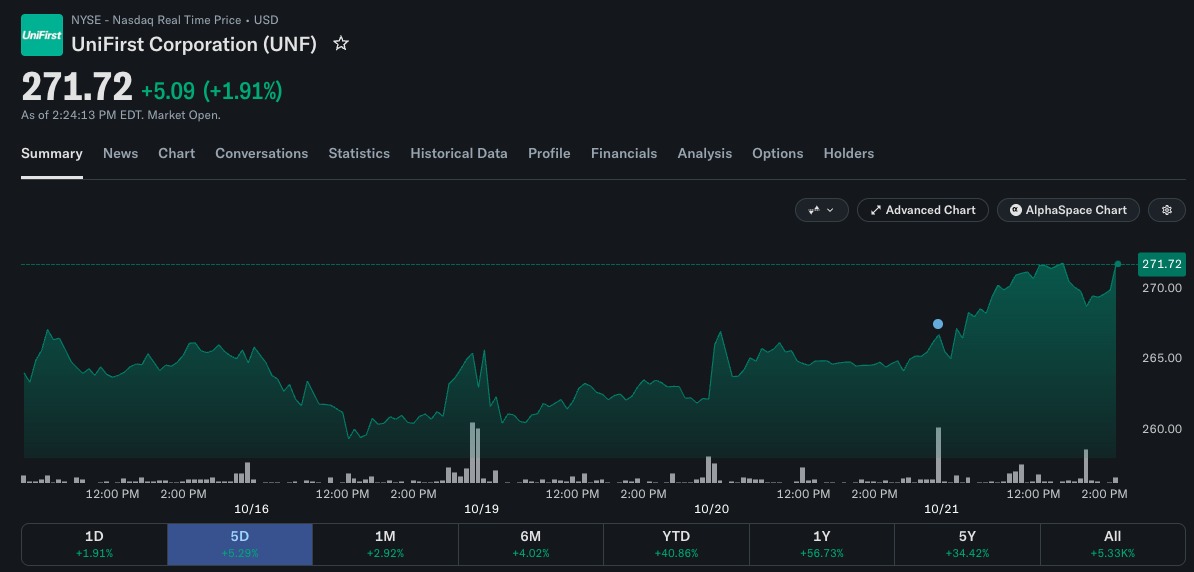
Enterprise Value Trajectory for Commercial Route Providers
Navigating corporate consolidations successfully requires looking past short-term advisory fee drags to assess underlying organic demand. Accumulating quality service equities during merger-driven earnings noise allows institutional investors to participate in post-combination scale efficiencies.
Maintaining client service excellence while expanding specialized secondary service offerings ensures that commercial facility leaders sustain pricing power and deliver strong long-term value for institutional capital partners.