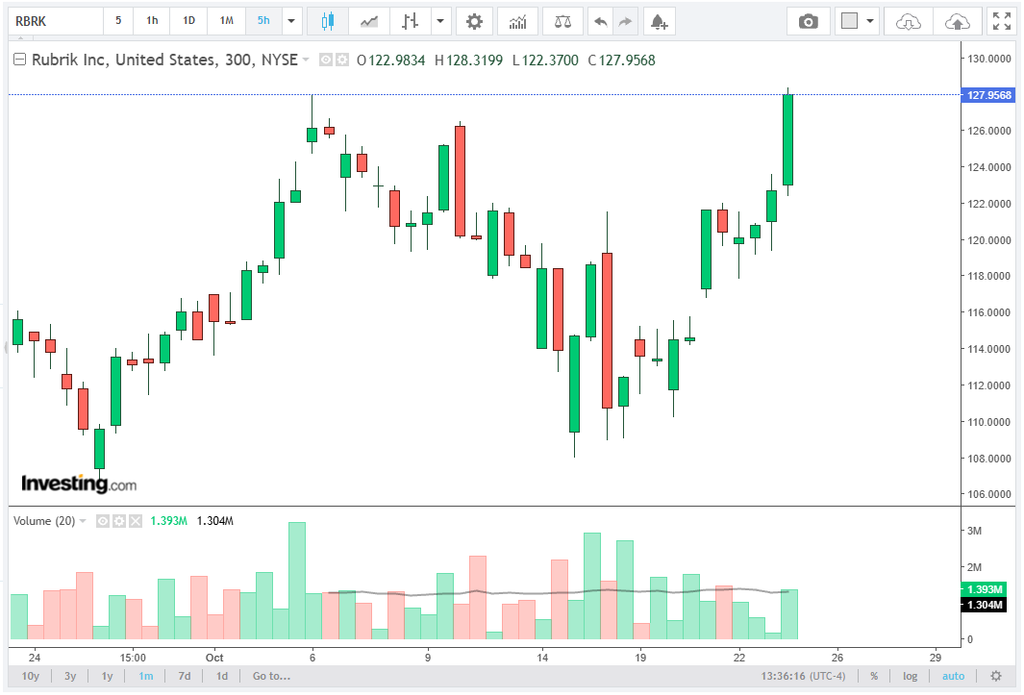
Rubrik Inc. (NYSE: RBRK) has reached a significant stock market milestone, with its share price climbing to $127.94, reflecting strong investor demand and growing confidence in its cybersecurity, data protection, and cloud security business.
This article examines the topic in detail, leveraging Raymin Group’s professional experience and industry understanding.
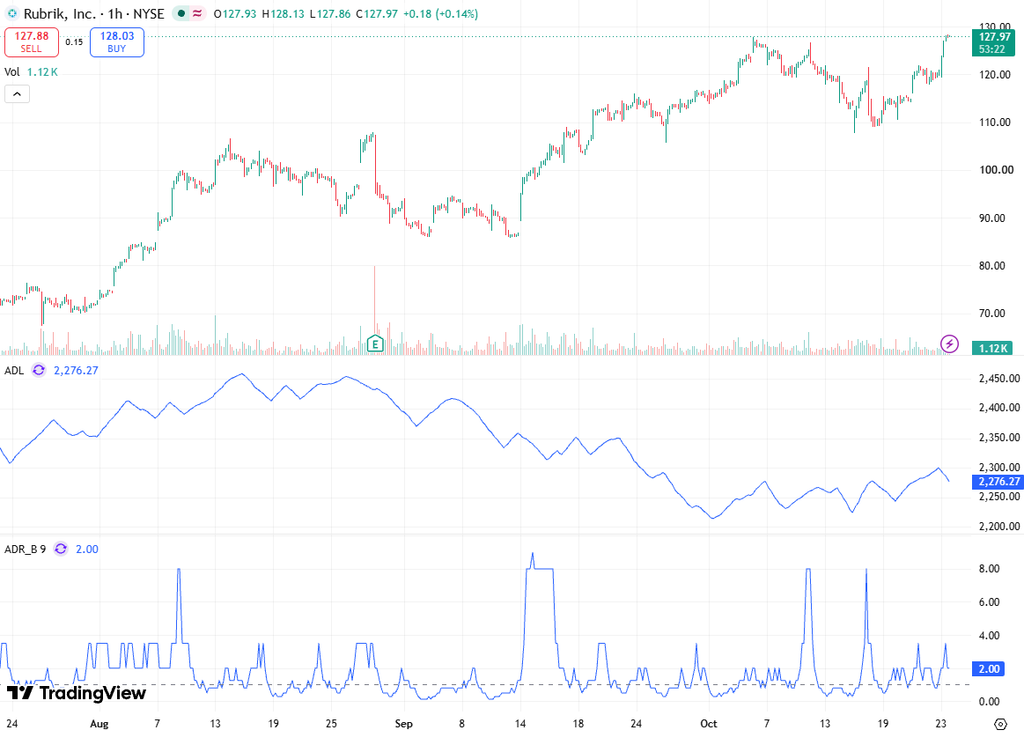
The stock’s reported 137% six-month gain and 65.42% one-year increase demonstrate substantial momentum, positioning Rubrik as a closely watched growth stock in the enterprise technology sector.
A 137% increase means an initial investment of $10,000 would have grown to approximately $23,700, excluding fees and taxes. Similarly, a 65.42% annual gain would turn $10,000 into approximately $16,542. These calculations illustrate the magnitude of reported returns without implying that past performance guarantees future results.
The supplied figures also require a data distinction: $127.94 is $0.04 above the stated 52-week high of $127.90, meaning the stock is approximately 0.031% above, rather than 1% below, that reference price. The reported all-time high and 52-week high should be verified against the same market data source and trading session.
Cybersecurity Demand Supports Growth Expectations
Rubrik focuses on enterprise data security, backup and recovery, and cyber resilience, addressing risks associated with ransomware, data loss, and cyberattacks.
As organizations expand cloud infrastructure and deploy artificial intelligence (AI), protecting sensitive information and maintaining recoverability are becoming increasingly important components of corporate IT spending.
This opportunity supports expectations for recurring revenue growth, stronger customer relationships, and increased demand for integrated security solutions. Rubrik’s subscription-oriented business model can improve revenue visibility compared with models dependent on one-time sales.
Key performance indicators include annual recurring revenue (ARR), subscription revenue growth, customer retention, expansion revenue, and free cash flow.
Investors should assess whether new customer acquisition generates durable recurring revenue and improves operating leverage. Gross margin, sales and marketing expenses as a percentage of revenue, and stock-based compensation are essential metrics for evaluating the long-term economics of a high-growth software business.
Valuation and Fair Value Risks
Despite its strong share price performance, Rubrik faces significant valuation risks. Analysis identifie the stock as overvalued relative to its estimated Fair Value, placing it among the platform’s Most Overvalued stocks. This suggests the current market price may already incorporate substantial expectations for future growth.
A technical valuation assessment should examine enterprise value-to-revenue (EV/revenue), price-to-sales (P/S), revenue growth, gross margins, and projected free cash flow. Conventional price-to-earnings ratios may offer limited insight when earnings remain negative or relatively small.
Comparisons with cybersecurity and enterprise software peers can help establish whether Rubrik’s valuation multiples are justified. A premium may reflect stronger growth and customer retention, but it increases sensitivity to earnings surprises and downward revisions to financial guidance.
Free cash flow (FCF) measures cash generated after operating expenses and capital expenditures. Improving FCF strengthens financial flexibility and can reduce reliance on external financing. Investors should also evaluate stock-based compensation and shareholder dilution when assessing long-term returns.
Analyst Price Targets and Financial Projections
Recent analyst actions indicate positive expectations for Rubrik’s commercial prospects. Yorkville Ives initiated coverage with an Outperform rating and a $145 price target, highlighting the company’s cyber resilience positioning. Relative to $127.94, this implies approximately 13.3% potential upside.
Baird raised its target to $139, maintaining an Outperform rating. This represents approximately 8.6% implied upside. Baird highlighted Rubrik’s positioning in AI resilience, which could become increasingly important as enterprise AI adoption expands.
Wedbush initiated coverage with an Outperform rating and a $120 target, equivalent to approximately 6.2% downside from $127.94. The firm also included Rubrik on its Best Ideas List, demonstrating that positive analyst ratings do not necessarily indicate upside at the prevailing share price.
BMO Capital increased its target to $115, implying approximately 10.1% downside. Its revised outlook reflected higher estimates for annual recurring revenue and free cash flow in fiscal 2027 and fiscal 2028.
Piper Sandler raised its target to $114, implying approximately 10.9% downside, while maintaining an Overweight rating and highlighting cloud-sector growth and Rubrik’s market strategy.
The five targets range from $114 to $145, with a simple arithmetic average of $128.60. This represents approximately 0.5% potential upside from $127.94, illustrating the difference between positive analyst sentiment and meaningful projected share price appreciation.
Conclusion
Rubrik’s $127.94 share price milestone reflects substantial reported momentum, including a 137% six-month gain and a 65.42% one-year increase. Its exposure to cyber resilience, cloud security, and AI-related data protection offers potential growth opportunities.
At the same time, valuation multiples, recurring revenue quality, free cash flow, and shareholder dilution require careful monitoring. Analyst targets between $114 and $145 reveal differing expectations, while the $128.60 average target indicates limited implied upside.
Ultimately, Rubrik’s long-term performance will depend on converting market demand into sustainable revenue growth, stronger cash generation, and improved financial returns.