

Gold dropped sharply this week, dropping below the $4,350 mark as higher US producer price data reinforced market expectations of a FRS rate hike at the upcoming policy meeting.
The precious metal, which had already been under pressure from rising Treasury yields and a firmer dollar, saw its third consecutive weekly decline.
Despite the near-term selloff, gold remains up roughly 19% over the past twelve months. The metal reached an all-time high of $5,602 in late January before entering a protracted correction. The 52-week range of $3,627 to $5,595 highlights just how volatile the precious metals market has been throughout the year.
Brokers from Financial Real Time provide a detailed analysis of the forces driving gold lower and the key technical levels that could determine the metal’s short-term trajectory.
With the Fed decision looming, the interplay between inflation data, energy prices, and monetary policy expectations has created a volatile trading environment for bullion.
US Producer Prices Accelerate, Tightening the Squeeze on Gold
The August producer price index increased 0.4% month-on-month, with annual producer inflation accelerating to 5.4%, exceeding the 5.3% consensus forecast.
The hotter print reflected surging energy costs and broader price crossover across multiple sectors, adding to the inflationary narrative that has dominated markets in recent weeks.
Markets responded swiftly, pricing in a greater than 66% chance of a Fed rate hike at the upcoming September meeting. Higher interest rates weigh directly on non-yielding assets like gold, as the opportunity cost of holding bullion rises alongside Treasury yields.
Adding to the headwinds, US Treasury yields jumped following lower-than-expected purchases by the Treasury Department during its first expanded buyback operation. The combination of fiscal signals and inflation data created a hostile environment for precious metals.
The US dollar index strengthened in parallel, buoyed by the repricing of rate expectations. Real yields, measured by the 10-year TIPS spread, have climbed steadily throughout the quarter, eroding the appeal of zero-coupon assets.
Gold’s correlation with real yields has reasserted itself after a brief decoupling earlier in the summer, when geopolitical risk premiums temporarily overrode the macro signal.
Technical Levels Hold Firm as Range Tightens
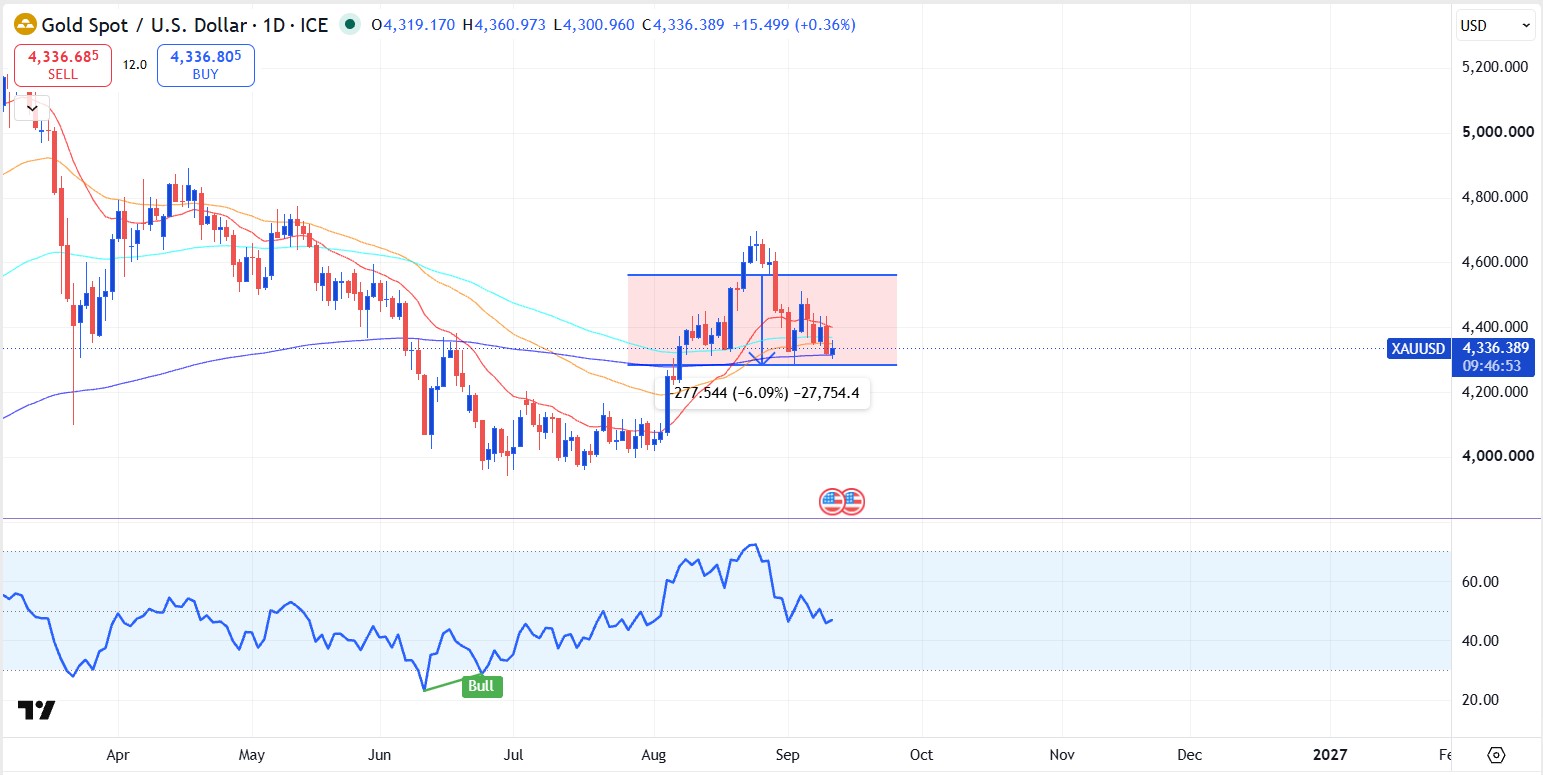
From a technical standpoint, gold has been trading within an increasingly defined range. Resistance at $4,424 to $4,456 has held on multiple tests, with the most recent rejection occurring near $4,409.
On the downside, the $4,300 support floor was tested almost to the cent, with a low print at $4,300.40 before buyers stepped in.
The RSI (14) on the daily chart sits near 40, reflecting weakening momentum without yet reaching oversold territory. The 50-day simple moving average hovers around $4,450, acting as dynamic resistance and capping any short-term rallies. The MACD histogram remains in negative territory, confirming the prevailing bearish bias.
The broader pattern since the late August peak at $4,697 is one of lower highs and a flat support base, forming a descending triangle on the four-hour chart.
This formation typically resolves with a directional breakout, and volume has been building on the downside tests, suggesting sellers are gaining conviction. The 200-day SMA sits well below current levels near $4,280, offering a potential secondary support should the $4,300 floor give way.
What Could Break the Range?
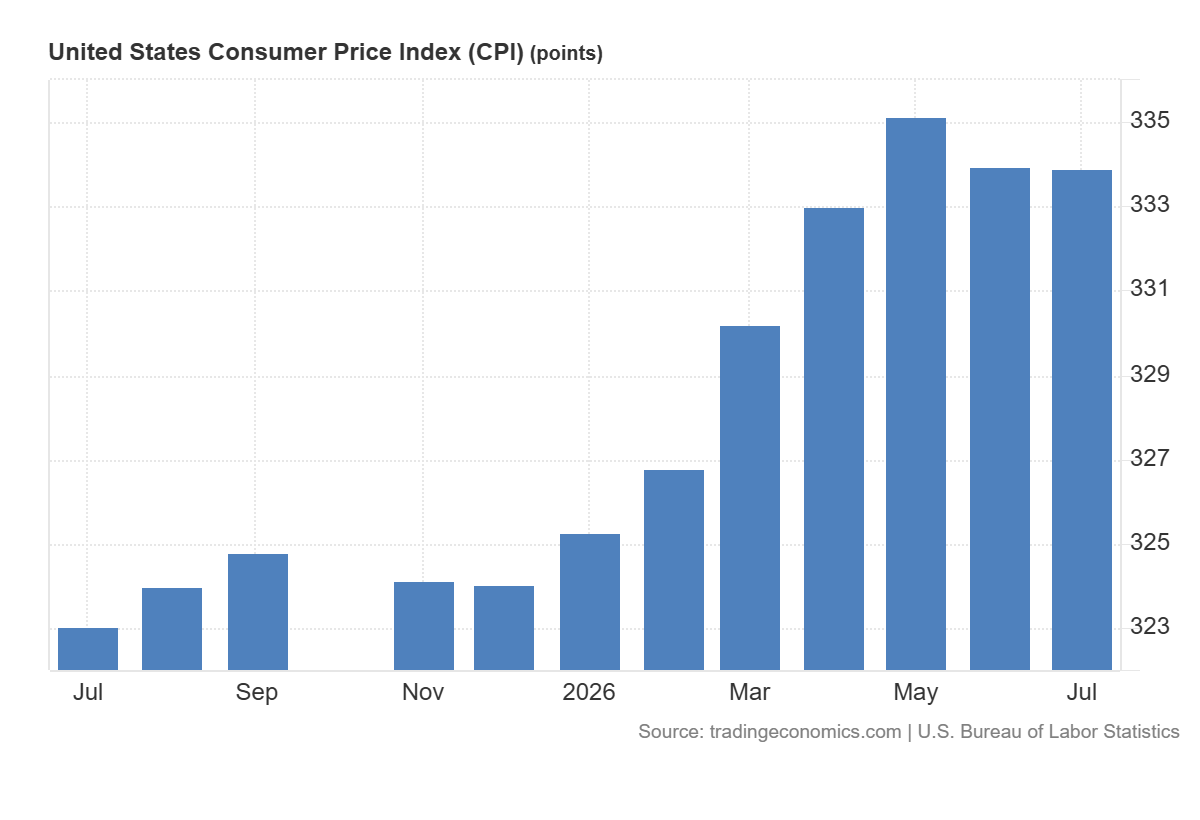
The upcoming US consumer price index report will be critical. A hotter-than-expected CPI reading would likely cement rate hike expectations and push gold toward a confirmed break below $4,300, opening the path toward $4,230 and potentially $4,200.
Conversely, any softness in the inflation print could trigger a relief rally. A reclaim of $4,456 on a closing basis would shift the technical picture and target $4,565 as the next resistance, followed by the $4,630 zone.
Central bank demand, which provided a structural bid for gold throughout much of 2024 and 2025, has shown signs of slowing in recent months. Physical purchases by emerging market central banks remain positive but have not accelerated at the pace seen during the first quarter.
Meanwhile, gold-backed ETF holdings have registered net outflows for three consecutive weeks, signalling that institutional investors are reducing exposure ahead of the Fed decision.
Middle East tensions remain a wildcard. Escalating conflict between the US and Iran has driven Brent crude past $108 per barrel, and any further deterioration could revive safe-haven demand for gold despite the headwinds from higher rates. For now, the metal sits at a crossroads, trapped between macro-driven selling pressure and geopolitical risk support.