

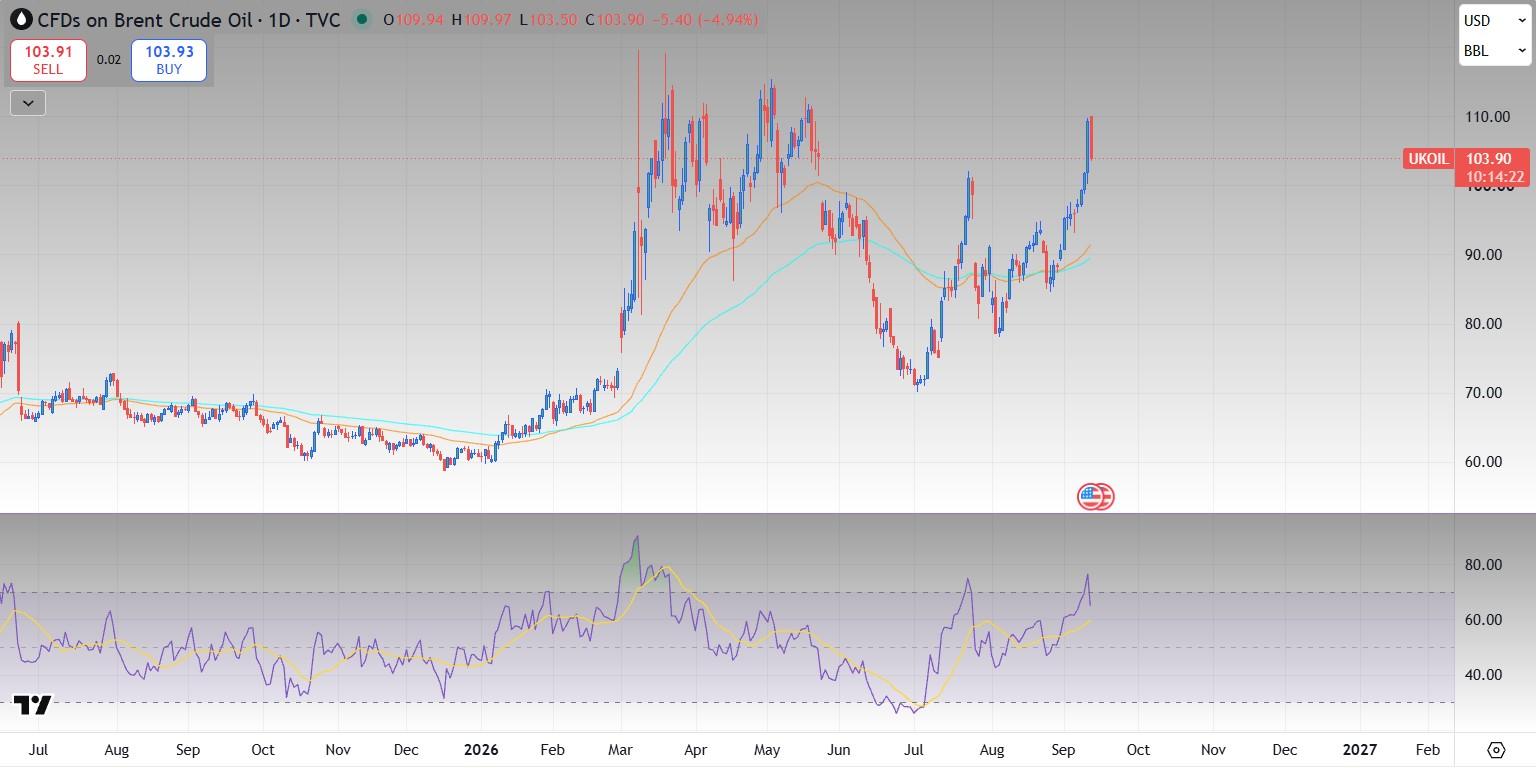
Brent crude oil prices surged past $108 per barrel, reaching their highest level since mid-May as escalating military confrontations in the Persian Gulf reignited fears of prolonged disruptions to global energy supply.
The international benchmark gained more than 3.4% in a single session earlier this week, with WTI crude also climbing to settle near $96.
Brokers from Financial Real Time assess the supply-side risks driving crude higher and the technical indicators pointing to further upside potential, even as demand concerns linger in the background.
The rally marks a dramatic reversal from the summer lows. Brent traded as low as $72 per barrel in late June, when expectations of rising Middle East supply briefly outweighed geopolitical risk premiums.
Since then, prices have surged more than 50%, driven almost entirely by supply-side disruptions rather than demand growth. The speed of the move has caught many market participants off guard, with short positions being unwound aggressively across futures markets.
Persian Gulf Hostilities Drive Supply Fears
The surge in crude prices followed an intensification of hostilities in the Persian Gulf. Reports indicate that the US military targeted Iranian oil tankers, while Iran launched retaliatory missile strikes at warships and tankers in the Strait of Hormuz.
The strait, which normally handles approximately 20 million barrels of oil per day, has seen constrained and variable flows for months.
Major shipping companies have rerouted tankers around the Cape of Good Hope to avoid the conflict zone, adding 10 to 14 days to delivery times and significantly increasing freight costs.
Insurance premiums for vessels transiting the Gulf have tripled since the start of the conflict, with several underwriters refusing to cover the route entirely.
The US Energy Information Administration’s September outlook estimates that crude oil production shut-ins averaged 6.7 million barrels per day in August, up from 5.0 million in July.
Global oil inventories have decreased by an estimated 400 million barrels so far this year, further tightening the market.
EIA Raises Price Forecasts, Markets Brace for More Volatility
The EIA now forecasts Brent to average around $90 per barrel in the second half of 2026, an $8 per barrel increase from last month’s projection.
The agency expects prices to begin declining in the second quarter of 2027 as shut-in production gradually restarts and flows through the Strait normalise.
Oil tanker rates have jumped to record highs, adding to the cost of moving crude through contested waters. The risk premium built into current prices reflects not only immediate supply losses but also the possibility that conflict could worsen, further constraining exports from the region.
OPEC+ has signalled willingness to raise output, but any additional barrels would take weeks to reach the market and are unlikely to offset the scale of current disruptions.
The US has also considered releasing oil from its strategic petroleum reserves, though inventories are already at multi-decade lows following drawdowns in 2022 and 2023. Without a meaningful de-escalation in hostilities, the supply gap is expected to persist into the fourth quarter.
US domestic production has provided a partial buffer. Output reached a record 13.4 million barrels per day in August, with the EIA forecasting further increases to 14.3 million by 2027.
Shale producers in the Permian Basin have ramped drilling activity in response to elevated prices, though the lag between investment and output means the full supply response will take quarters to materialise.
Can Oil Sustain Above $100?
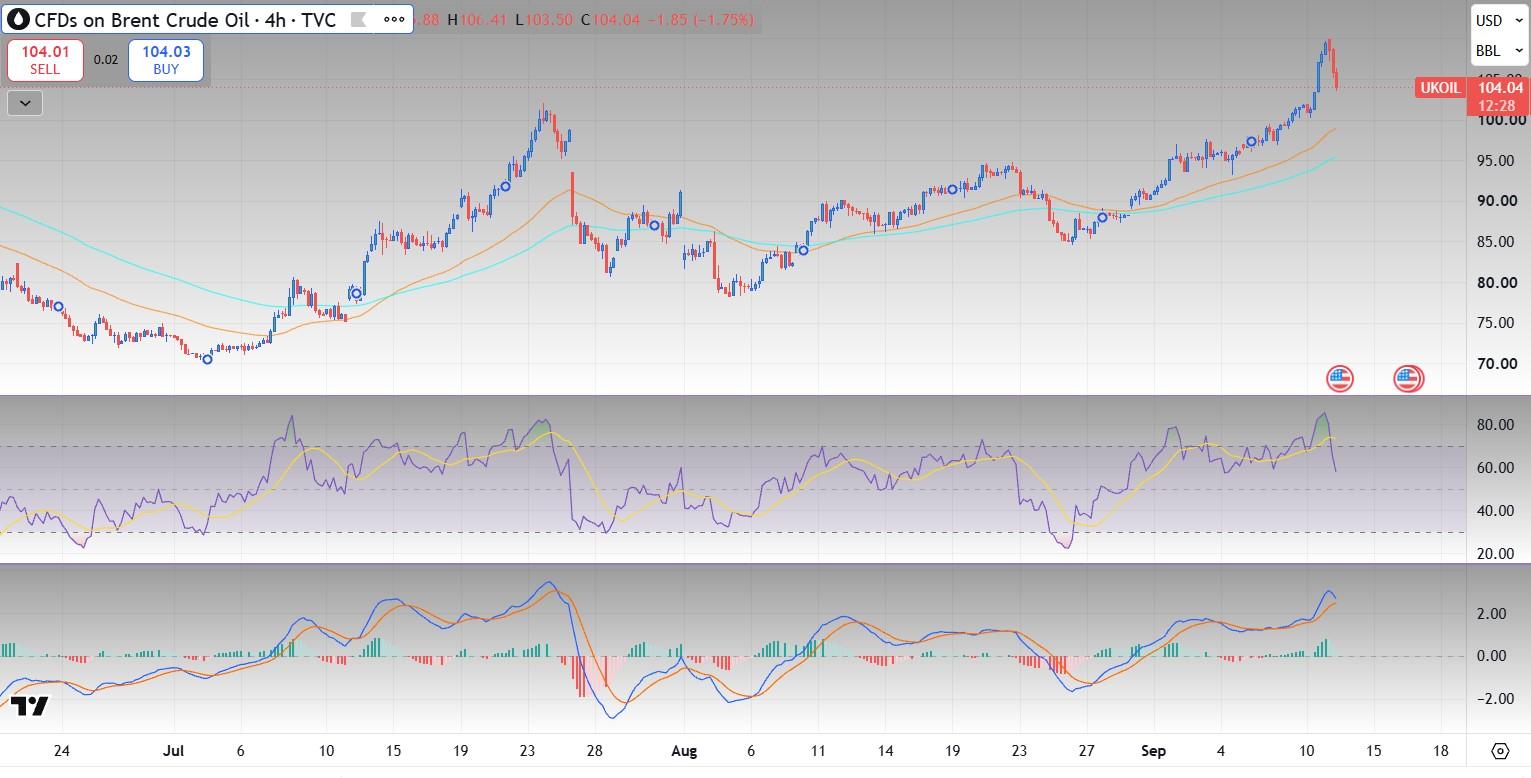
Technically, the RSI (14) on the daily chart sits near 72, signalling overbought conditions. While this does not necessarily mean an imminent reversal, it suggests that profit-taking could emerge at current levels. The 50-day SMA around $92 provides a distant but significant support floor should prices correct.
The May high near $110 represents the next major resistance barrier. A sustained break above that level could open the path toward $115 to $120, a scenario that investment banks have flagged as increasingly plausible if shipping attacks intensify.
The broader implications extend well beyond the energy complex. Elevated crude prices feed directly into headline inflation figures across major economies, complicating the task of central banks already navigating between growth risks and price stability.
The pass-through to consumer fuel costs has been swift, with US gasoline prices averaging $4.22 per gallon, the highest since early June. European diesel margins have also widened, adding cost pressure to logistics and manufacturing sectors.
Demand-side risks persist, however. Higher energy costs act as a drag on global growth, and any signs of economic weakening in major consuming nations could cap the rally. For now, supply disruption fears dominate, keeping crude firmly bid above the triple-digit mark.