

With Medical Properties Trust Inc (NYSE: MPT) set to enter its next distribution cycle, equity investors with an income bias are taking a hard look at the trust’s payout arrangements. The healthcare REIT has put market focus on its historical patterns and the sustainability of its cash flow by way of a recent $0.09 per share quarterly dividend announcement.
Even as headline yields are anything but ordinary, value-oriented types are weighing the appeal of near-term cash against wider financial headwinds.
One does not approach high-yield income equities without some discipline in risk management and a thorough fundamental review. As a market analyst at AchievementsAI would have it, the long-term enterprise value of an REIT is predicated on sound debt handling and consistent rental income.
And while a liberal dividend can be a draw for retail money, institutional analysts make it clear that any investor worth his salt will examine the payout metrics in detail to safeguard the portfolio over the long haul.
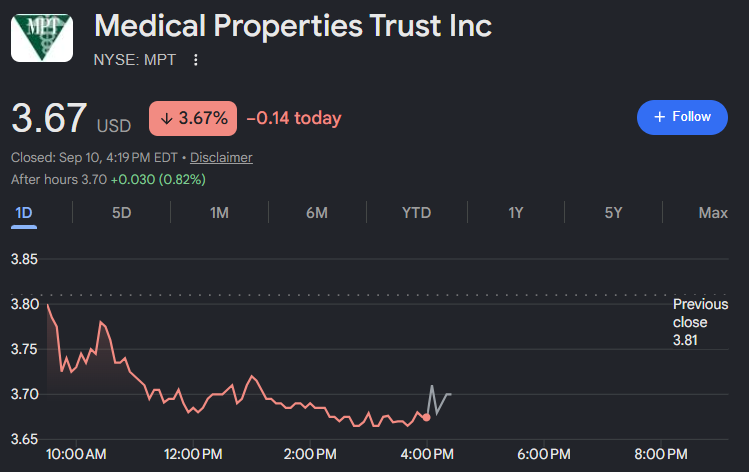
Deconstructing The Net-Lease Healthcare Real Estate Model
The core of the business model is based on the acquisition, development, and leasing of specialized healthcare facilities to experienced operating companies. These facilities include acute care hospitals and rehabilitation centers.
Tenants are directly responsible for the financial obligations of property maintenance, insurance, and operational taxes under the terms of standard triple-net lease agreements.
The purpose of this structured framework is to generate rental revenue that is both predictable and contractual, while at the same time protecting the landlord from the day-to-day expenses associated with facility operations across a variety of geographic regions that span both the United States and international markets.
Evaluating Historical Dividend Records And Distribution Cadence
Since 2005, Medical Properties Trust has maintained a history of uninterrupted dividend payments, and it distributes income on a quarterly basis in order to accommodate shareholders who are focused on income. In order to evaluate the dependability and volatility of income over extended market cycles, it is essential to conduct a review of historical annual dividends per share.
While a long-standing payment history demonstrates operational longevity, income investors must weigh past consistency against recent capital allocation adjustments and portfolio restructuring initiatives.
Analyzing Trailing Yields Versus Forward Dividend Expectations
At present, the equity commands a trailing 12-month dividend yield of 9.00%, accompanied by a 12-month forward dividend yield of 9.25%. A forward yield exceeding the trailing metric suggests potential stability or minor payout adjustments anticipated by market participants over upcoming distribution cycles.
However, a yield approaching 9% frequently signals elevated market risk, requiring investors to determine whether underlying cash generation is sufficient to support ongoing distributions without eroding principal value.
Inspecting Multi-Year Dividend Growth Contraction Rates
A critical analytical finding involves examining annualized dividend growth rates across extended historical horizons. Over the preceding three-year period, annual dividend growth contracted by -34.20%, while the five-year annualized growth rate declined by -22.40%. Furthermore, the ten-year annualized dividend growth rate stands at -6.60%.
These negative growth figures confirm that the company has systematically reduced payouts over time, contrasting sharply with the headline current yield and demanding caution from retirement income seekers.
Assessing Payout Ratios And Earnings Profitability Rankings
Evaluating dividend sustainability requires careful examination of payout ratios and relative earnings capacity. The current payout ratio sits at 2.78, reflecting complex accounting relationships between net earnings and cash distributions typical of specialized real estate investment trusts.
Additionally, profitability metrics place the enterprise at 6 out of 10, supported by net positive earnings in seven out of the past ten years, underscoring moderate profitability accompanied by historical earnings volatility.
Examining Revenue Declines And Asset Growth Metrics
Growth metrics provide essential insight into whether the enterprise possesses the operational momentum required to maintain high-yield distributions. Revenue per share trends alongside a three-year revenue contraction rate averaging -14.40% indicate that top-line performance underperforms approximately 90.18% of global peers.
This ongoing revenue contraction presents a meaningful operational headwind, as declining top-line figures can pressure the cash flows required to service debt and fund shareholder dividends.
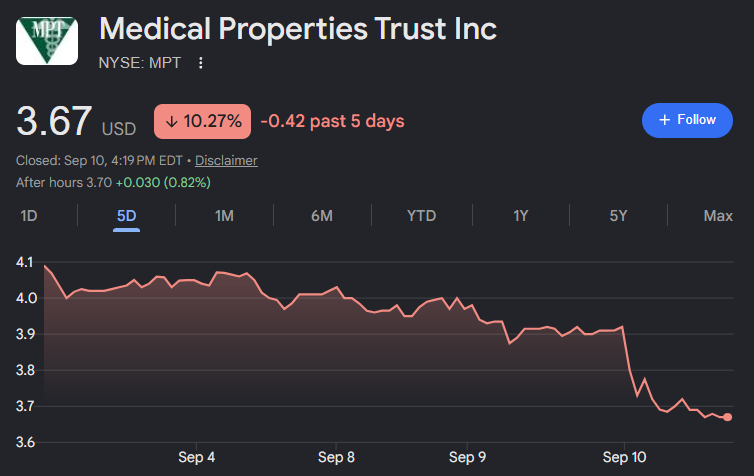
Income Insights And Strategic Investment Horizons
One should be mindful of the difficult trade-offs facing the income-oriented investor in high-yield real estate stocks when looking at the $0.09 per share dividend on the horizon. While a 9.25% forward yield has its attractions for those wanting cash flow, there is no getting around the need for a hard look at the risks.
The company’s operational headwinds, revenue models in contraction and a long record of negative dividend growth all call for a thorough appraisal. In the end, preserving the portfolio over the long term means one must find some equilibrium between the lure of the yield and the underlying strength of the balance sheet.