

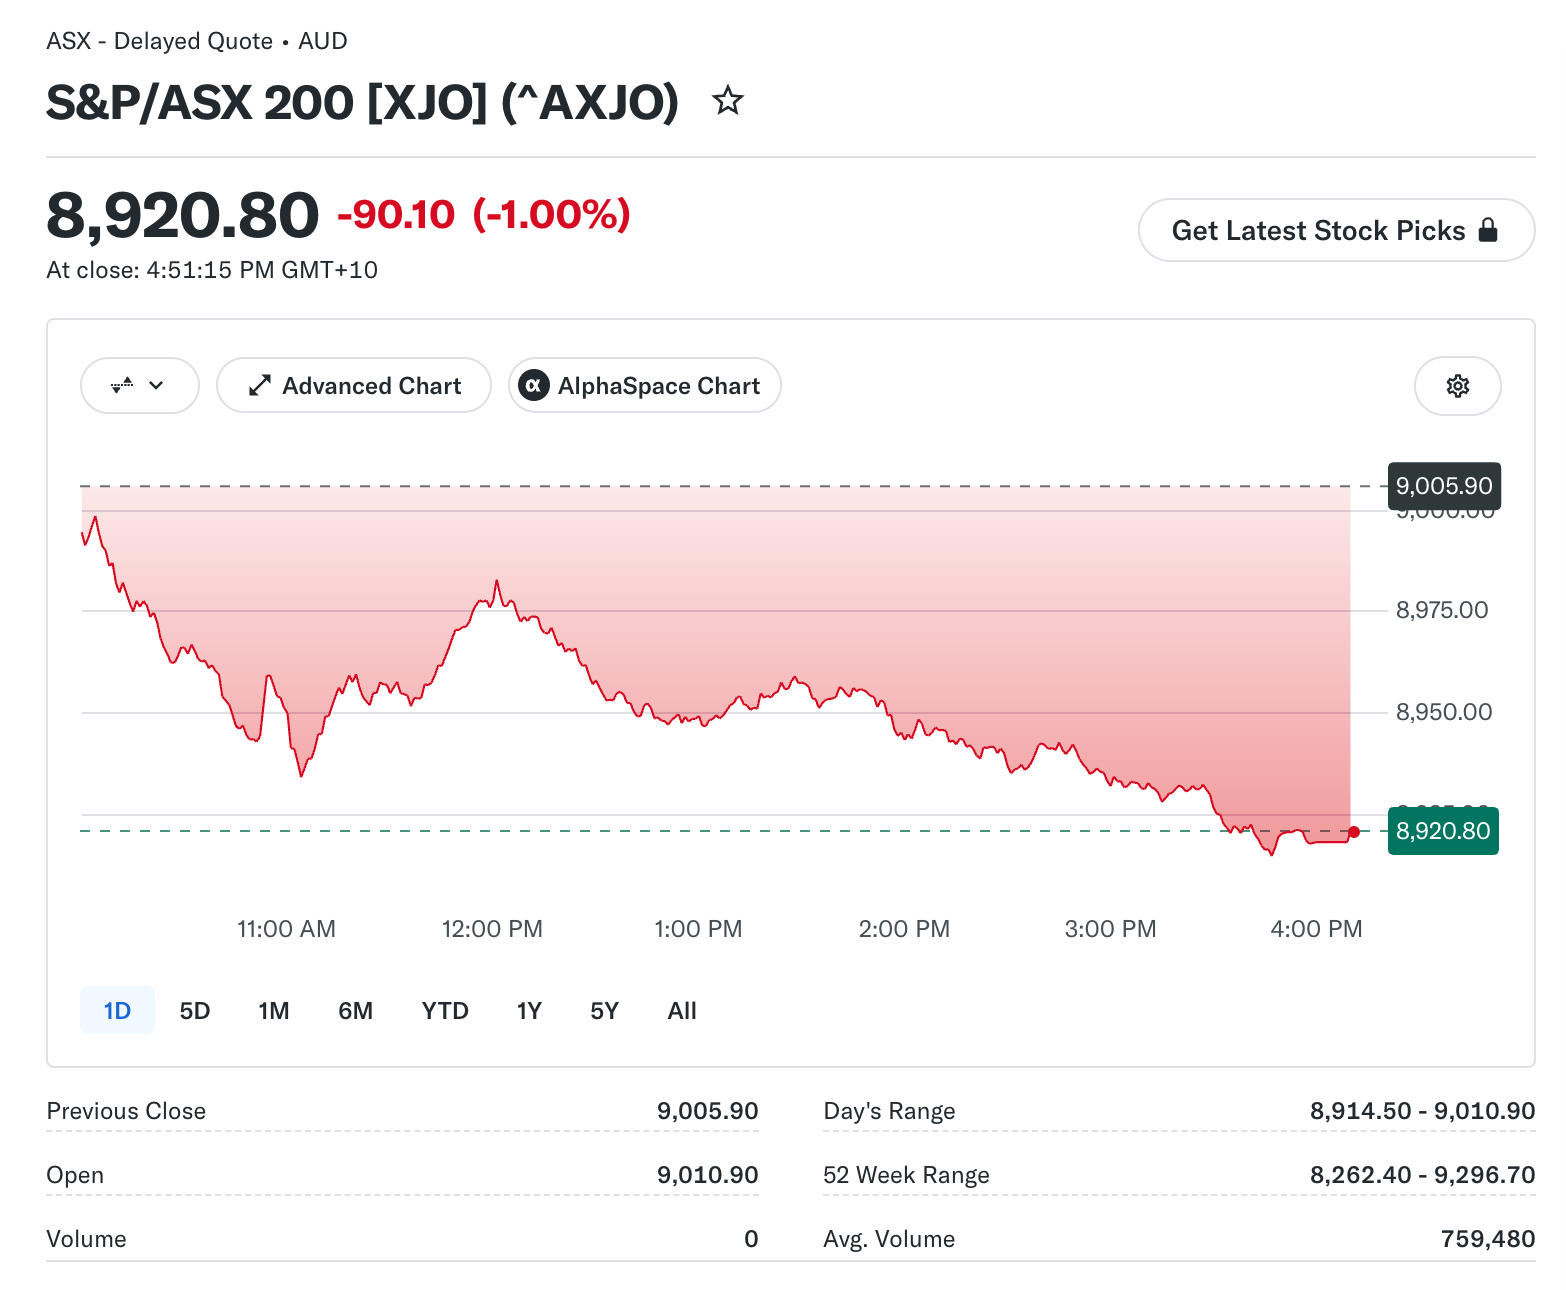
Australia’s S&P/ASX 200 was broadly flat in early trading as Asian markets around it were moving in sharply different directions. Japan’s Nikkei surged nearly 2 percent, driven by a technology rally. Hong Kong’s Hang Seng declined roughly 0.9 percent on US rate fears. South Korea’s Kospi advanced more than 4 percent on semiconductor strength.
In the middle of all those divergent moves, the ASX 200 held relatively steady, and that stability is not accidental.
A financial expert at Chilli Markets explores what the ASX’s flat performance reveals about the structural advantages and limitations of Australia’s equity market in the current global environment. The index’s distinct sector composition provides genuine insulation from the semiconductor and AI hardware sentiment driving the biggest moves elsewhere in the region.
The ASX’s Sector Composition as a Buffer
The ASX 200’s relative stability traces directly to what the index does not contain in significant quantity. Unlike the Korean Kospi or Japanese Nikkei, which carry heavy weights in semiconductor manufacturers, memory chip producers, and technology conglomerates, the ASX 200 is dominated by banks, mining companies, energy producers, and defensive consumer names.
When AI hardware sentiment drives sharp moves in Seoul and Tokyo, those moves have limited transmission into Sydney because the Australian market’s primary sectors move on different drivers. BHP Group, Commonwealth Bank, Rio Tinto, and Westpac collectively represent a substantial share of the ASX 200’s market capitalization.
These businesses respond to commodity prices, interest rate margins, dividend yield expectations, and domestic credit growth conditions. That fundamental disconnection from the AI hardware cycle that dominated recent headlines is precisely what kept the ASX 200 stable when its regional peers were moving sharply.
Mining Stocks and the Iron Ore Connection
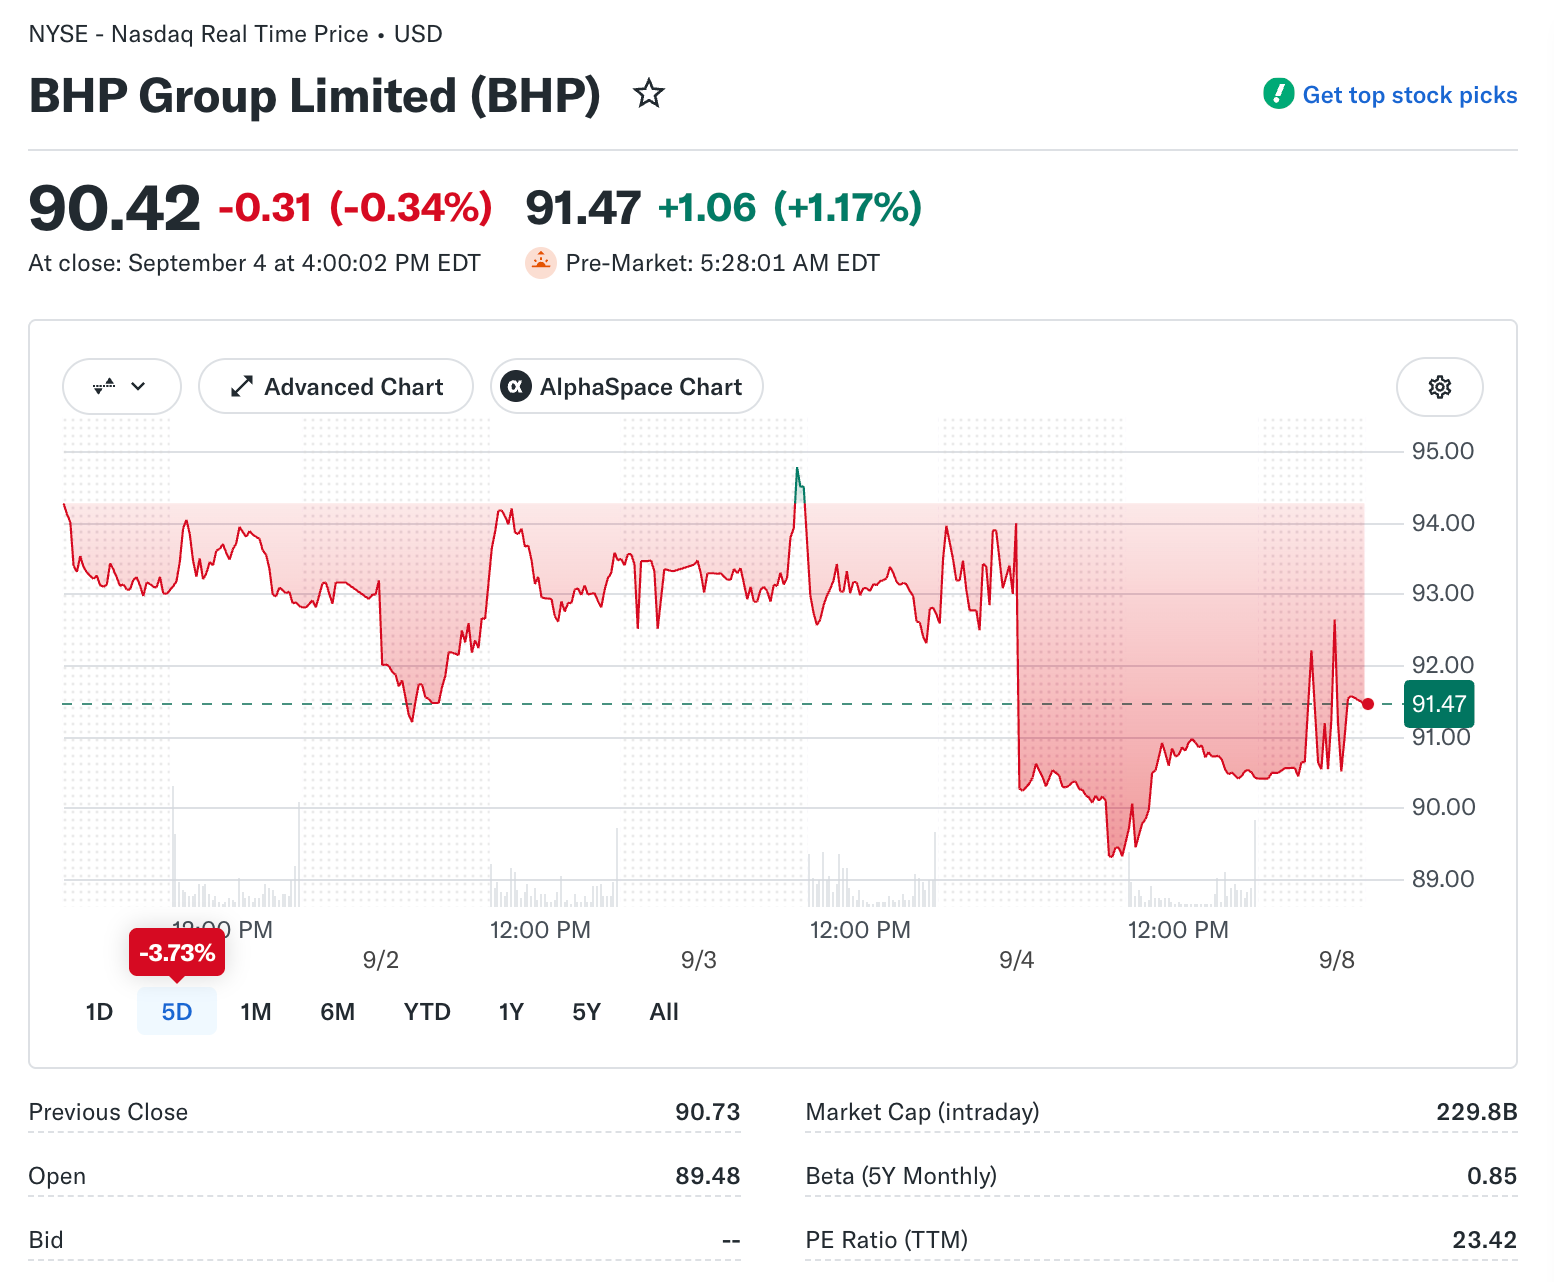
BHP and Rio Tinto, two of the ASX 200’s largest components, are heavily tied to iron ore prices. Iron ore prices are closely linked to Chinese steel production and infrastructure spending. The China trade data that Hong Kong investors are watching is directly relevant to ASX mining stocks as well.
If China’s upcoming export and import figures confirm continued industrial activity, iron ore demand projections stay constructive.
That would support BHP and Rio Tinto valuations. The ASX 200 participates in positive global risk appetite through its mining and energy sector exposure rather than through technology names. That distinction changes which global data points investors should monitor when assessing ASX direction and building tactical positions within the index.
The Australian Dollar and the US Rate Environment
The US Federal Reserve’s rate decisions flow into the Australian equity market through the exchange rate channel. When the Fed raises rates and the US dollar strengthens, the Australian dollar typically weakens. A weaker Australian dollar benefits ASX mining and energy exporters, because their dollar-denominated commodity revenues convert into more Australian dollars when repatriated.
The Reserve Bank of Australia’s own rate policy is also relevant. Australian interest rates have been elevated relative to pre-pandemic levels, and the domestic property market remains sensitive to the rate environment. Bank stocks, which are major ASX components, face margin pressures when borrowing costs rise faster than lending rates but benefit from a steeper yield curve over time.
Petco’s Strong Result as an ASX-Adjacent Consumer Signal
While Petco is a US-listed company with no direct ASX listing, its recent earnings result provides context for the global consumer environment. Petco’s adjusted EBITDA margin in the second quarter beat the StreetAccount consensus estimate, with an actual figure of 8.2 percent against an expected 7.4 percent.
That consumer sector strength in the United States points to a household spending environment that, despite elevated interest rates and energy costs, has not collapsed. Australian consumer stocks on the ASX face a similar dynamic, with households navigating high mortgage rates and elevated food and energy costs while maintaining baseline spending volumes.
When comparable US consumer businesses are posting margin beats, it provides mild reassurance that the consumer stress scenario many analysts feared has not fully materialized. When the global consumer picture holds up better than worst-case models predicted, Australian consumer stocks carry less fundamental downside risk than their current valuations sometimes imply.
What to Watch for the ASX Through the Coming Weeks
Iron ore prices and Chinese economic data are the near-term variables most directly relevant to ASX mining sector performance. Any diplomatic progress on the Iran conflict that reduces oil prices would simultaneously benefit Australian energy importers and reduce inflation pressure on the Reserve Bank of Australia.
That could moderate the rate tightening trajectory and benefit the domestic-facing bank and consumer sectors. Bank stocks will respond to domestic mortgage arrears data and credit growth figures as the primary indicators of household financial health.
The ASX 200’s flat performance this week is less a sign of weakness than a reflection of its genuine independence from the technology-driven volatility that defined sessions in other Asian markets. That independence is a feature rather than a problem for investors seeking portfolio diversification from AI hardware cycle risk.