

Mainland China’s CSI 300 index closed 0.59 percent higher at 4,575.02 while global markets around it were experiencing sharp divergences. Japan’s Nikkei surged nearly 2 percent and South Korea’s Kospi jumped more than 4 percent, while Hong Kong’s Hang Seng fell roughly 0.9 percent.
The CSI 300’s measured advance demonstrated relative resilience that reflects the market’s structural insulation from some of the external pressures affecting other Asian benchmarks. The brand’s senior financial advisor mentions that Chilli Markets views the CSI 300’s recent behavior as a useful window into the distinct risk factors that drive mainland Chinese equity performance.
Separating the mainland market’s drivers from those of Hong Kong and other Asian benchmarks is essential for investors building Asia-Pacific exposure. The two markets look geographically close but behave quite differently.
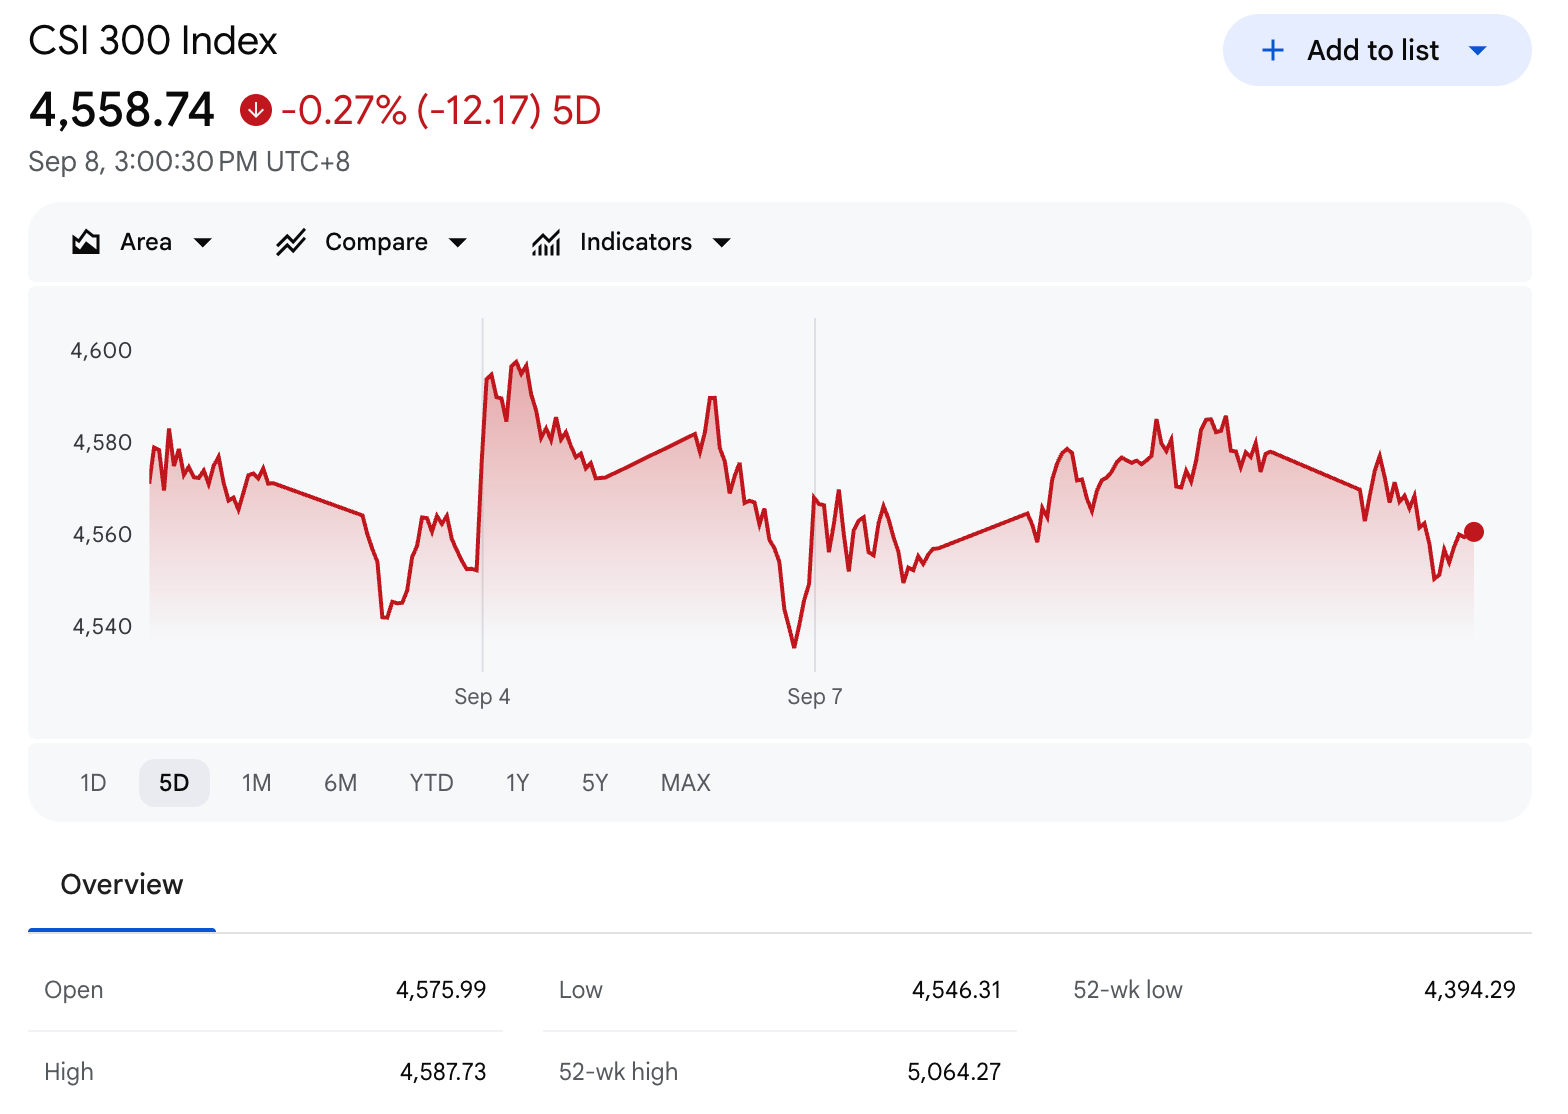
Why the CSI 300 Responds Differently to Global Events
Mainland China’s equity markets operate under a set of constraints and supports that are fundamentally different from most other major global markets. The renminbi is not freely convertible, which means the direct transmission of US dollar strength and Federal Reserve rate decisions into Chinese equity pricing is less immediate than in Hong Kong or South Korea.
Domestic monetary policy tools give the People’s Bank of China independent levers to manage equity market conditions that the Hong Kong Monetary Authority cannot match given the currency peg.
When the US jobs report sent rate expectations sharply higher and pressured risk assets globally, the CSI 300 absorbed that information through its impact on investor sentiment rather than through direct interest rate transmission.
The buffer that controlled currency convertibility provides is meaningful in practice. It helps explain why mainland Chinese equities often show different intraday dynamics than other Asian markets responding to the same global catalyst.
AI and Semiconductor Demand as a China Equity Driver
The trade data released recently provided important context for mainland Chinese equities. The US trade deficit surged to $88.6 billion in the most recent monthly reading, with capital goods imports jumping $14.4 billion including computers and computer accessories.
That surge in US technology goods imports reflects the AI infrastructure buildout that continues to generate demand for components manufactured across Asia, with Chinese suppliers participating in that supply chain at multiple points.
South Korea’s chip exports surged 68.7 percent year on year to $98.25 billion, driven by hyperscaler capital expenditure demand. Chinese semiconductor and technology companies participate in adjacent parts of the same AI supply chain. The strength of global AI infrastructure demand provides a supportive backdrop for CSI 300 technology components even when other pressures are weighing on the index.
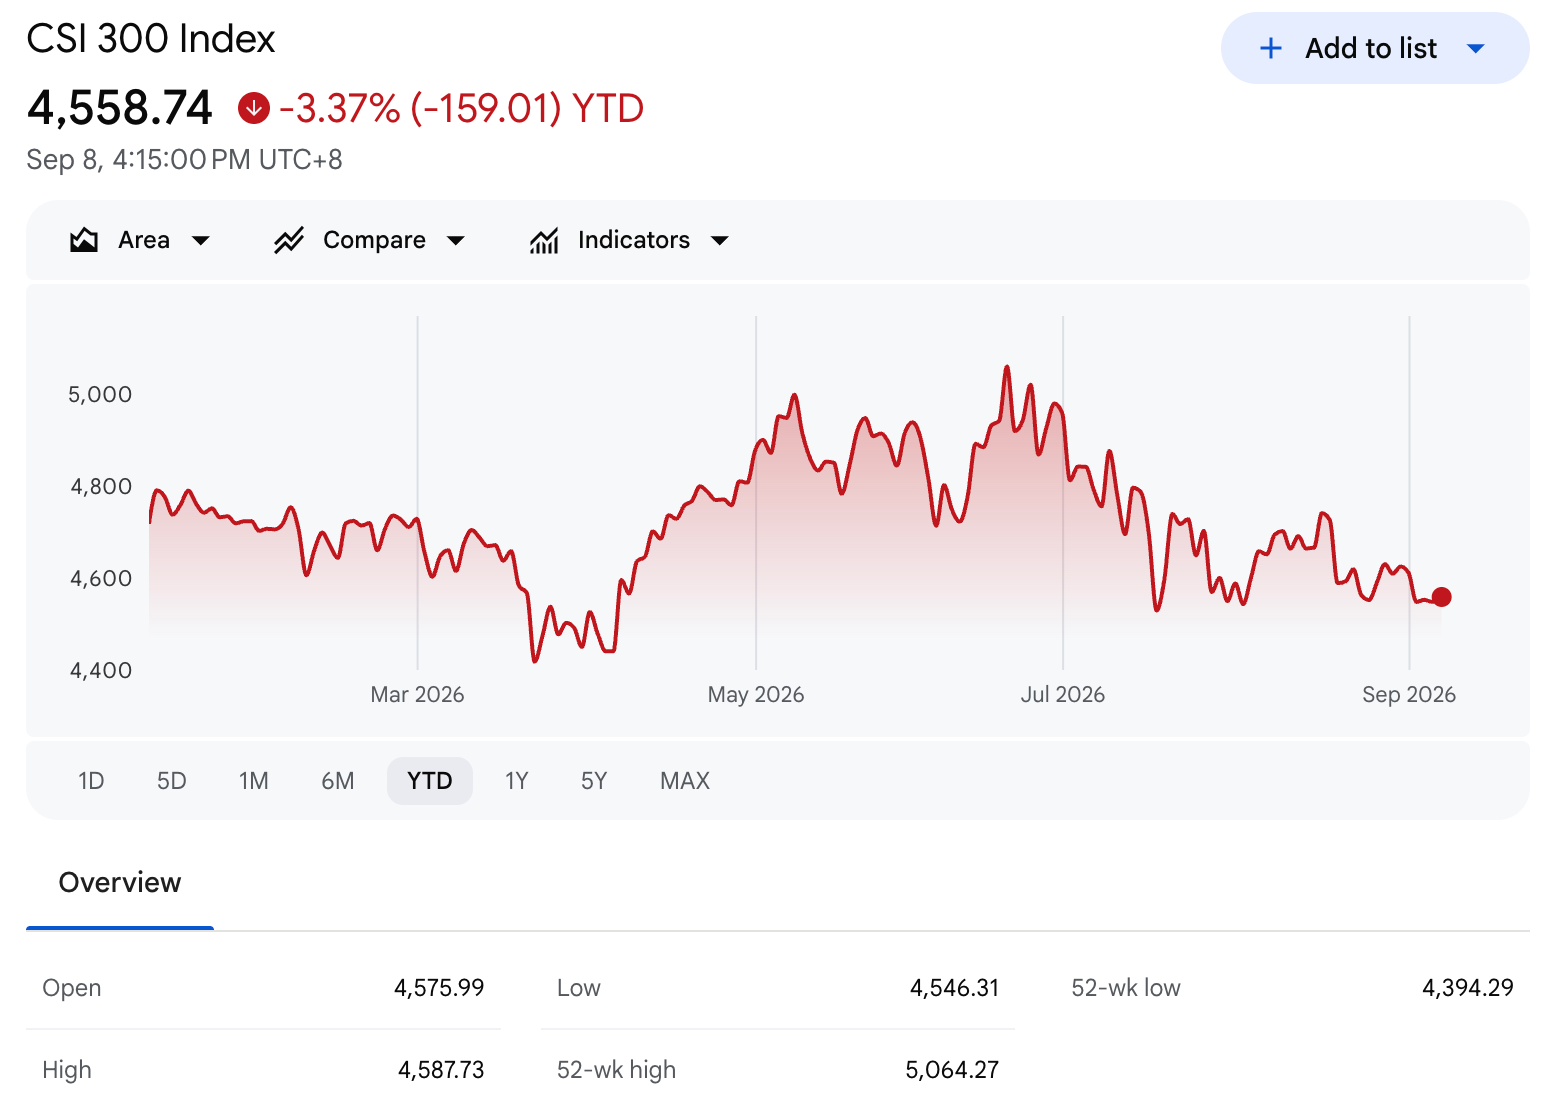
Property Sector Headwinds Remain
Despite the CSI 300’s relative stability, the mainland Chinese equity market continues to navigate a property sector that has been in a prolonged contraction. The real estate downturn continues to weigh on consumer confidence, household balance sheets, and local government fiscal positions across China.
Property developers listed on the CSI 300 have been among the most pressured names in the index, and their performance continues to drag on the broader benchmark. The People’s Bank of China’s policy tools have been directed partly at supporting the property market through liquidity provision and lending rate adjustments.
The effectiveness of those measures has been limited by the structural overcapacity problem that accumulated during the property boom years. That represents a genuine fundamental challenge rather than a liquidity issue that monetary easing alone can resolve.
Export Strength as a Stabilizing Factor
China’s export performance has been a stabilizing factor for the CSI 300 even as the domestic property sector remains under pressure. Manufacturing exports of technology goods, automotive components, and industrial equipment have grown strongly through the AI infrastructure buildout cycle.
The global demand for semiconductors, circuit boards, and related electronics that the hyperscaler capex wave is creating flows through Chinese manufacturing facilities in meaningful quantities.
When South Korea’s chip export data shows a near-70 percent year-on-year surge driven by AI demand, that same demand wave is benefiting Chinese component manufacturers who produce the ancillary hardware that accompanies chips in completed data center systems. The CSI 300’s stability partially reflects confidence that this export demand remains robust.
What Investors Should Monitor
The key variables for mainland Chinese equities center on domestic policy support and the global trade environment.
Any expansion of tariff threats from the United States would directly impact Chinese export manufacturers listed on the CSI 300. Conversely, new stimulus measures from Beijing targeting consumption or property sector stabilization would provide a positive domestic demand catalyst.
The US political backdrop, particularly any trade-related announcements, remains a significant external variable for Chinese equity market positioning.
Investors holding CSI 300 exposure should treat policy communication from both Beijing and Washington as leading indicators that can shift the mainland’s equity direction faster than fundamental earnings data typically would.