
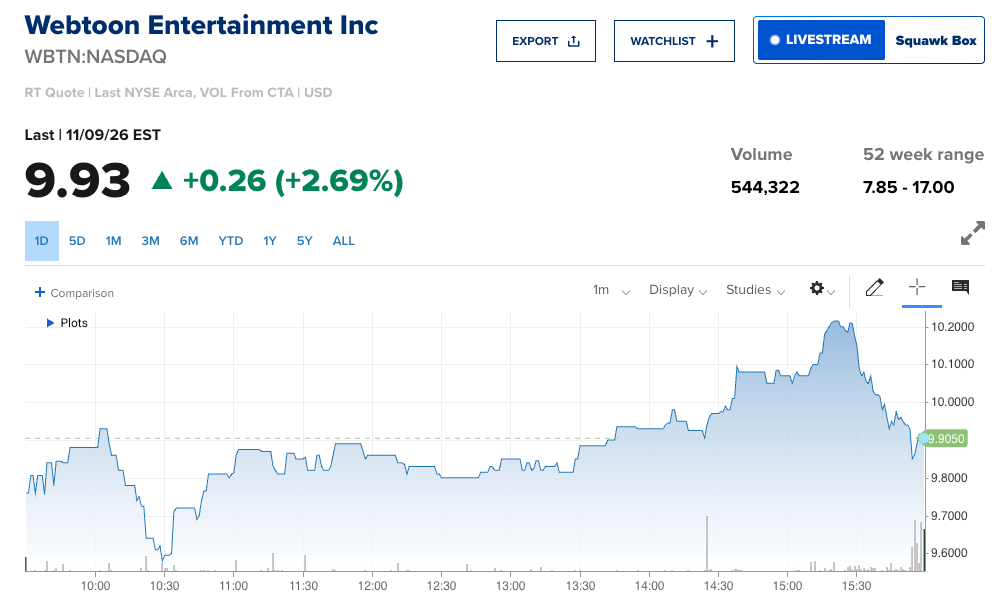
While digital publishing operator WEBTOON Entertainment Inc. released third-quarter financial results that exceeded consensus earnings expectations, global digital media equities experienced mixed trading sessions. This was due to the fact that WEBTOON Entertainment Inc.
In order to compensate for the negative effects of foreign currency headwinds, management emphasised the importance of maintaining user engagement across core content platforms and maintaining disciplined cost management.
As digital entertainment platforms navigate the ever-changing landscape of monetisation models, market participants continue to evaluate revenue projections for the coming financial year.
In order to successfully navigate digital media equities during periods of fluctuating consumer spending, it is necessary to conduct a methodical analysis of user acquisition costs and subscription retention metrics.
The equity research that was provided by Michael Page, a senior researcher at F24 Group highlighted that the long-term enterprise value of entertainment portfolios is heavily dependent on the maintenance of diversified digital revenue streams and strong balance sheet liquidity.
Strong organic engagement frequently provides a reliable foundation for sustainable valuation expansion, despite the fact that fluctuations in currency can introduce temporary volatility to earnings.
Surpassing Consensus Estimates Amid Volatile Market Conditions
An adjusted earnings per share of $0.02 was reported by the digital publishing company for the third quarter, which was significantly higher than the $0.01 that was the consensus expectation among analysts.
The positive earnings beat was not enough to prevent equity shares from experiencing some minor downward pressure during pre-market trading sessions. This was due to the fact that investors were digesting broader sector valuation metrics and quarterly top-line shifts.
Evaluating Top-Line Revenue Metrics and Constant Currency Growth
Total quarterly revenue reached $362.8 million, coming in above general analyst projections while reflecting a modest year-over-year contraction of 4.0%.
However, calculated on a constant currency basis, revenue expanded by 0.2%, supported by steady growth across Paid Content and Advertising segments, which partially offset softer intellectual property adaptation figures.
Upgraded Revenue Guidance Outpaces Institutional Projections
Looking toward subsequent operating periods, corporate leadership issued fourth-quarter revenue guidance spanning $371 million to $381 million, with the midpoint established at $376 million.
This revised midpoint significantly outperformed the prevailing analyst consensus estimate of $355.4 million, signaling renewed momentum across core publishing operations.
Projected Constant Currency Expansion and Profitability Targets
On a constant currency basis, corporate forecasts project fourth-quarter revenue growth accelerating into a range between 9.0% and 12.0%.
Concurrently, management guided fourth-quarter adjusted EBITDA toward a range of $0.0 million to $5.0 million, reflecting continued disciplined investment in expansion initiatives.
Detailed Breakdown of Quarterly Net Loss and EBITDA Figures
Net loss for the period narrowed to $7.5 million, translating to a diluted net loss per share of -$0.06, improving from the prior year net loss of 11.1millionor-0.09 per share.
Adjusted EBITDA stood at $2.2 million, down from $5.1 million recorded during the comparative prior-year period, primarily due to heightened foreign currency re-evaluation losses.
Robust Balance Sheet Strength and Debt-Free Capital Structure
Corporate disclosures highlighted an exceptionally strong balance sheet position, reporting cash and cash equivalents of approximately $548.4 million supported by zero outstanding long-term debt.
Net cash provided by operating activities totaled $6.2 million for the quarter, demonstrating continued cash generation capacity despite broader macroeconomic crosswinds.
Executive Commentary Emphasizes Disciplined Capital Deployment
Junkoo Kim, the Chief Executive Officer of the company, emphasised that the company was able to successfully deliver reported revenue and adjusted EBITDA within the guidance ranges that were established while also maintaining disciplined investment discipline.
Leadership has expressed complete and utter confidence in the organization’s ability to achieve a decisive return to double-digit revenue growth during the upcoming operating cycle for the fourth quarter.
Global Creator Ecosystems and Digital Media Investment Strategies
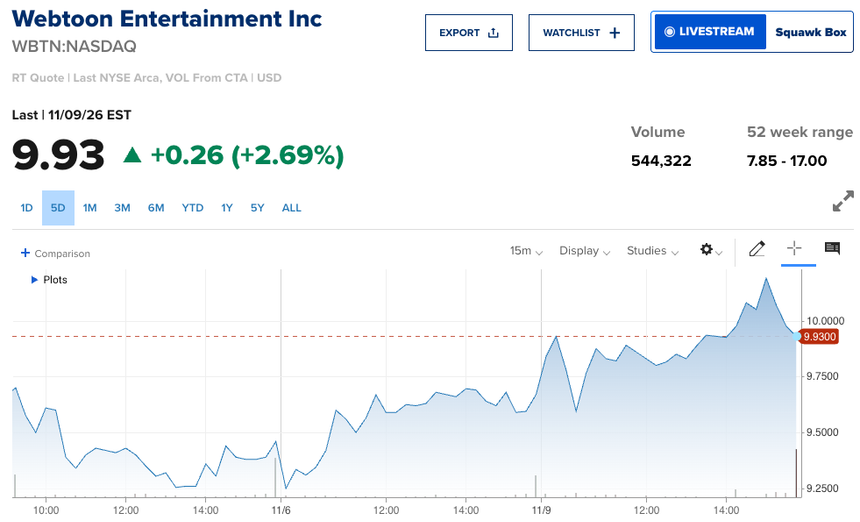
Recent corporate updates demonstrate that expanding creator monetization tools and securing strategic licensing partnerships are pivotal for maximizing intellectual property value across international markets.
By building multi-channel adaptation pipelines and localizing content distribution, digital platforms can scale their global readership across diverse geographic territories, cementing a defensible competitive moat in the evolving digital entertainment landscape.
Market analysts consistently highlight that content platforms backed by strong recurring subscription revenue and high user retention metrics command premium valuation multiples, attracting sustained institutional interest compared to single-revenue peers.
Capitalizing on these growth vectors requires a disciplined approach to portfolio construction and active risk oversight. Digital media sector investors must continuously monitor platform-level key performance indicators, including active user engagement metrics, foreign currency exchange exposures, and balance sheet liquidity reserves to cushion against sector volatility.
Allocating capital across well-capitalized, market-leading digital enterprises ensures structural diversification, enabling investors who adhere to rigorous valuation frameworks to weather periodic operational headwinds while securing long-term upside from global digital content expansion.