

US equity markets are closed for the Labor Day holiday. The conversation driving this week’s trading outlook is fully alive, however. August’s nonfarm payrolls report delivered a shock, showing the economy adding 162,000 jobs against a consensus estimate of just 53,000.
That positive surprise more than tripled expectations in a single report. A senior financial analyst at Chilli Markets says the scale of the payroll beat has shifted the Fed’s calculus heading into its upcoming September meeting. Markets are still absorbing the implications as trading resumes this week.
What the August Jobs Report Actually Showed
The unemployment rate held steady at 4.1 percent, matching expectations. The 162,000 job additions figure was the real story. Prior months were also revised upward, meaning the cumulative picture of job creation across recent months is stronger than previously reported.
A gain of 162,000 against a 53,000 forecast is one of the largest positive surprises relative to consensus that the US labor market has produced in recent memory. The 10-year Treasury yield responded immediately, climbing to 4.78 percent in the sessions after the release. The US Dollar Index firmed to 99.16 as the bond market repriced rate expectations.
CME FedWatch data showed the probability of a Federal Reserve rate hike at the September meeting rising to 58 percent. That figure had stood at 49.4 percent just the day before. That one-day shift is one of the sharpest moves in Fed pricing seen this year.
What It Means for Stocks When They Reopen
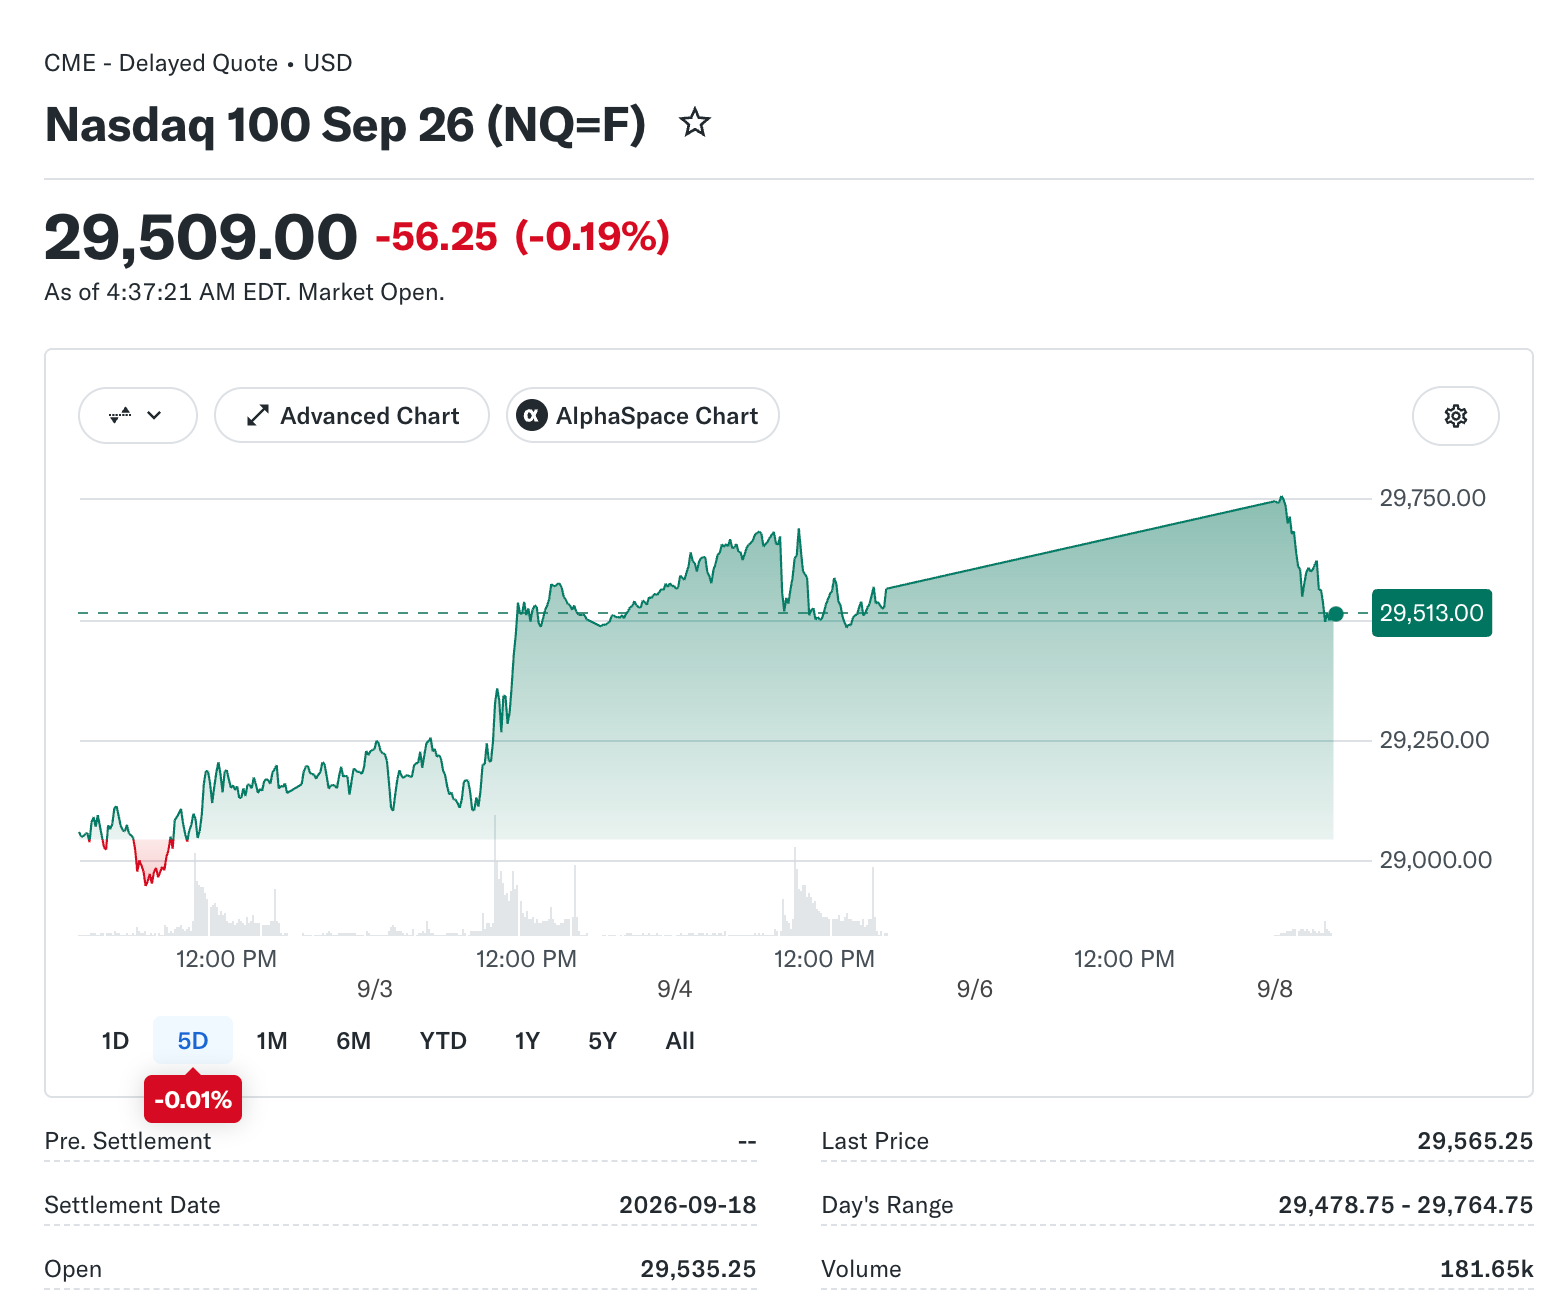
US equity markets posted gains earlier in the week, with the S&P 500 rising 1.10 percent to 7,751.28. The Nasdaq Composite advanced 1.52 percent to 26,615.52 before the jobs data landed. After the release, the picture reversed, with the S&P 500 sliding 0.38 percent to 7,718.60 and the Nasdaq falling 0.29 percent.
Technology stocks led the decline and the VIX climbed 1.47 percent to 14.53. Rate-hike repricing is the mechanism behind the post-report pullback. When investors raise the probability of a Fed rate increase, high-multiple growth stocks face the steepest valuation pressure because their earnings are discounted at a higher rate.
Technology names that outperformed in the first half of 2026 become the natural place for capital to exit when rate expectations shift hawkish. That dynamic played out clearly in the sessions following the report. Investors with diversified sector exposure absorbed the move better than those concentrated in technology.
The Iran Conflict Adds Another Layer
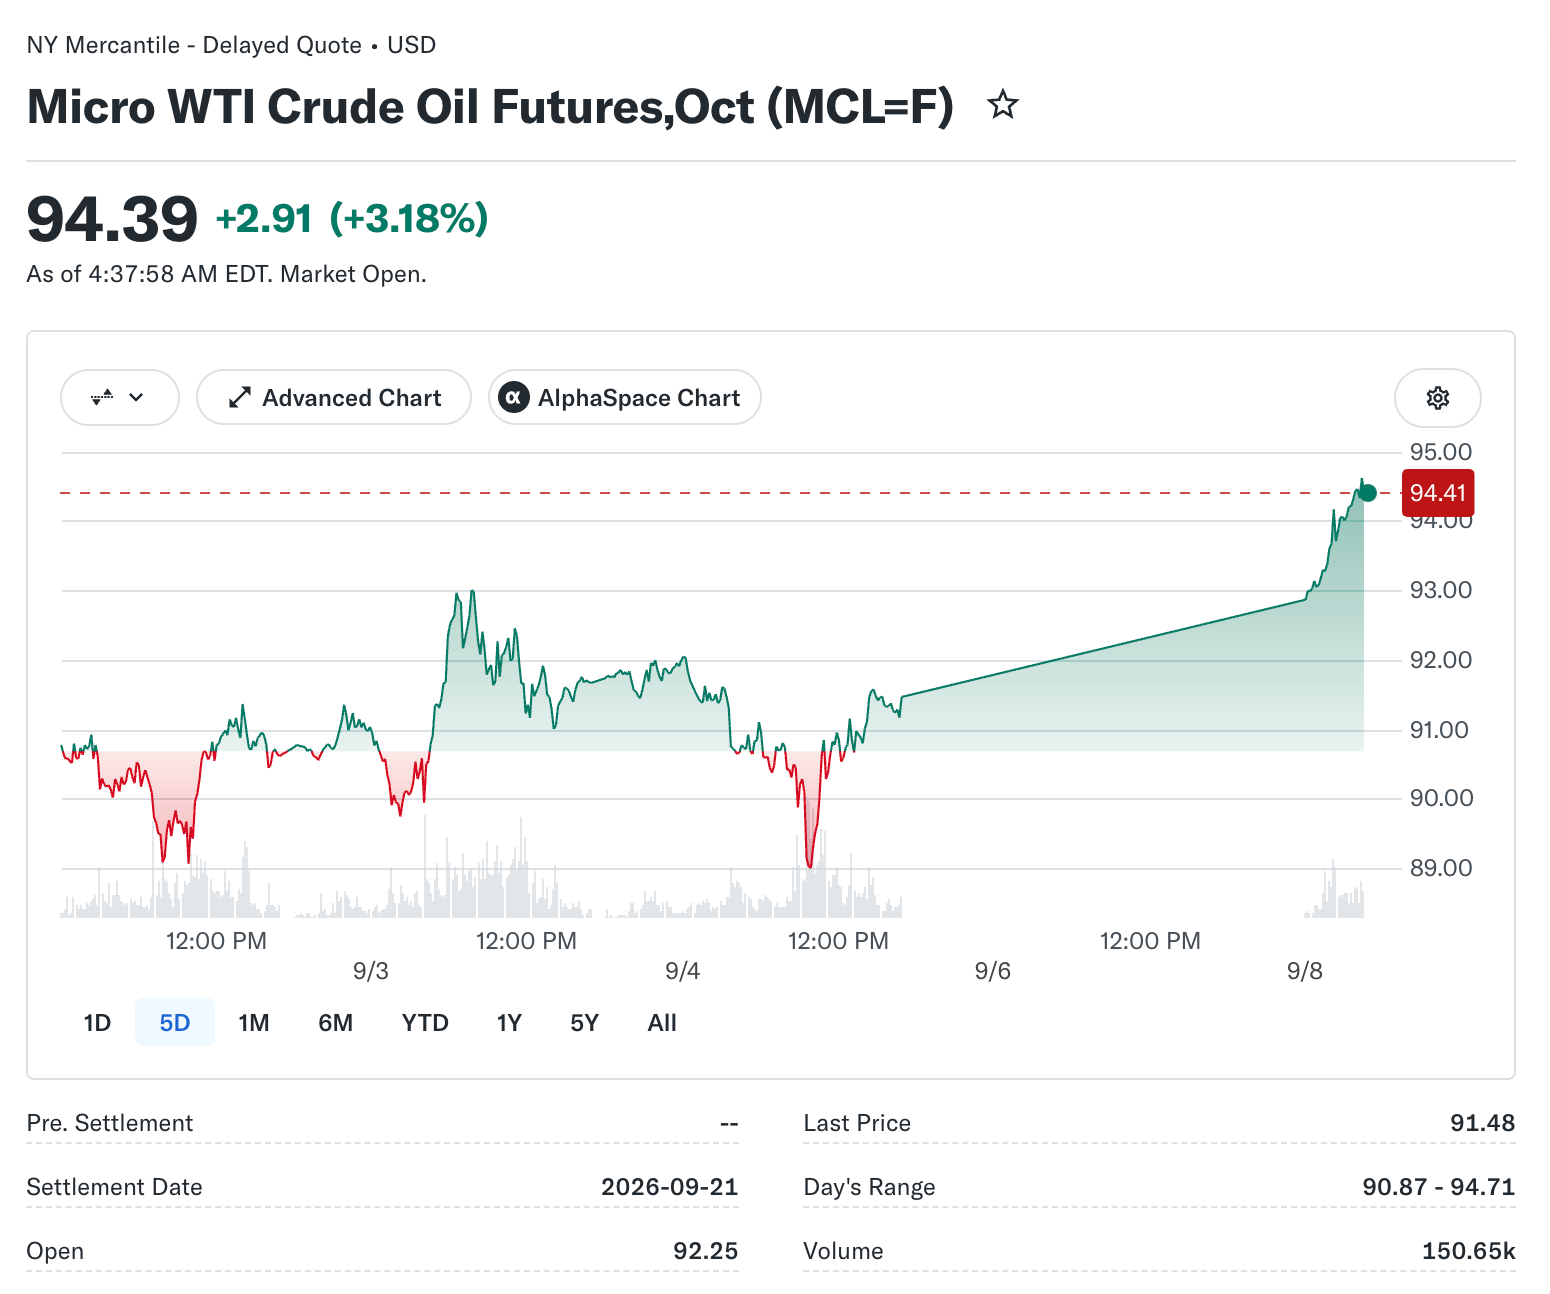
Oil prices pulled back after the jobs release, with WTI crude slipping to $90.55 and Brent easing to $95.04. The European Union formally joined the US-led Iran sanctions campaign around the same time, expanding the coalition of countries applying economic pressure on Tehran. South Korea also announced it was weighing a military role to help reopen the Strait of Hormuz.
These geopolitical developments sit alongside the jobs data as a second driver of market uncertainty. Higher oil prices feed into inflation expectations, which reinforces the case for Fed tightening. When both a strong jobs report and elevated energy prices push in the same direction simultaneously, the combined signal for rate expectations is stronger than either factor alone.
Investors heading into this week should treat oil price direction and Fed communication as two inputs currently reinforcing each other rather than offsetting. Both are pointing toward a more hawkish policy stance than markets had priced recently. Understanding that dynamic is essential for reading sector performance as it unfolds across the coming sessions.
Sectors That Benefit When Rates Rise
Not every sector suffers when rate-hike expectations increase. Financial stocks historically benefit from a higher rate environment because wider net interest margins improve bank earnings. Energy names benefit directly when oil prices remain elevated, and industrial companies with pricing power can maintain margins even as borrowing costs rise.
The rotation away from technology and into financials, energy, and industrials that began after the jobs release reflects this dynamic clearly.
This rotation has been building throughout 2026, and the August jobs report has accelerated its pace in a compressed window before the holiday break. Investors who recognized the rotation early are better positioned this week than those who held concentrated technology exposure through the post-report selloff.
The Market Environment Heading Into the Week
The VIX at 14.53 remains below the 20 threshold that typically marks elevated fear. Markets are adjusting expectations rather than fleeing risk assets entirely. That distinction matters for investors evaluating whether the recent pullback represents a buying opportunity or the start of a broader correction.
When markets reopen this week, the September Fed meeting outcome will be the single most important variable. A rate hike would confirm what the jobs data implied and likely extend pressure on technology valuations. A hold, despite the strong jobs data, would signal that the Fed is weighting inflation data more heavily than employment strength in its decision framework.