

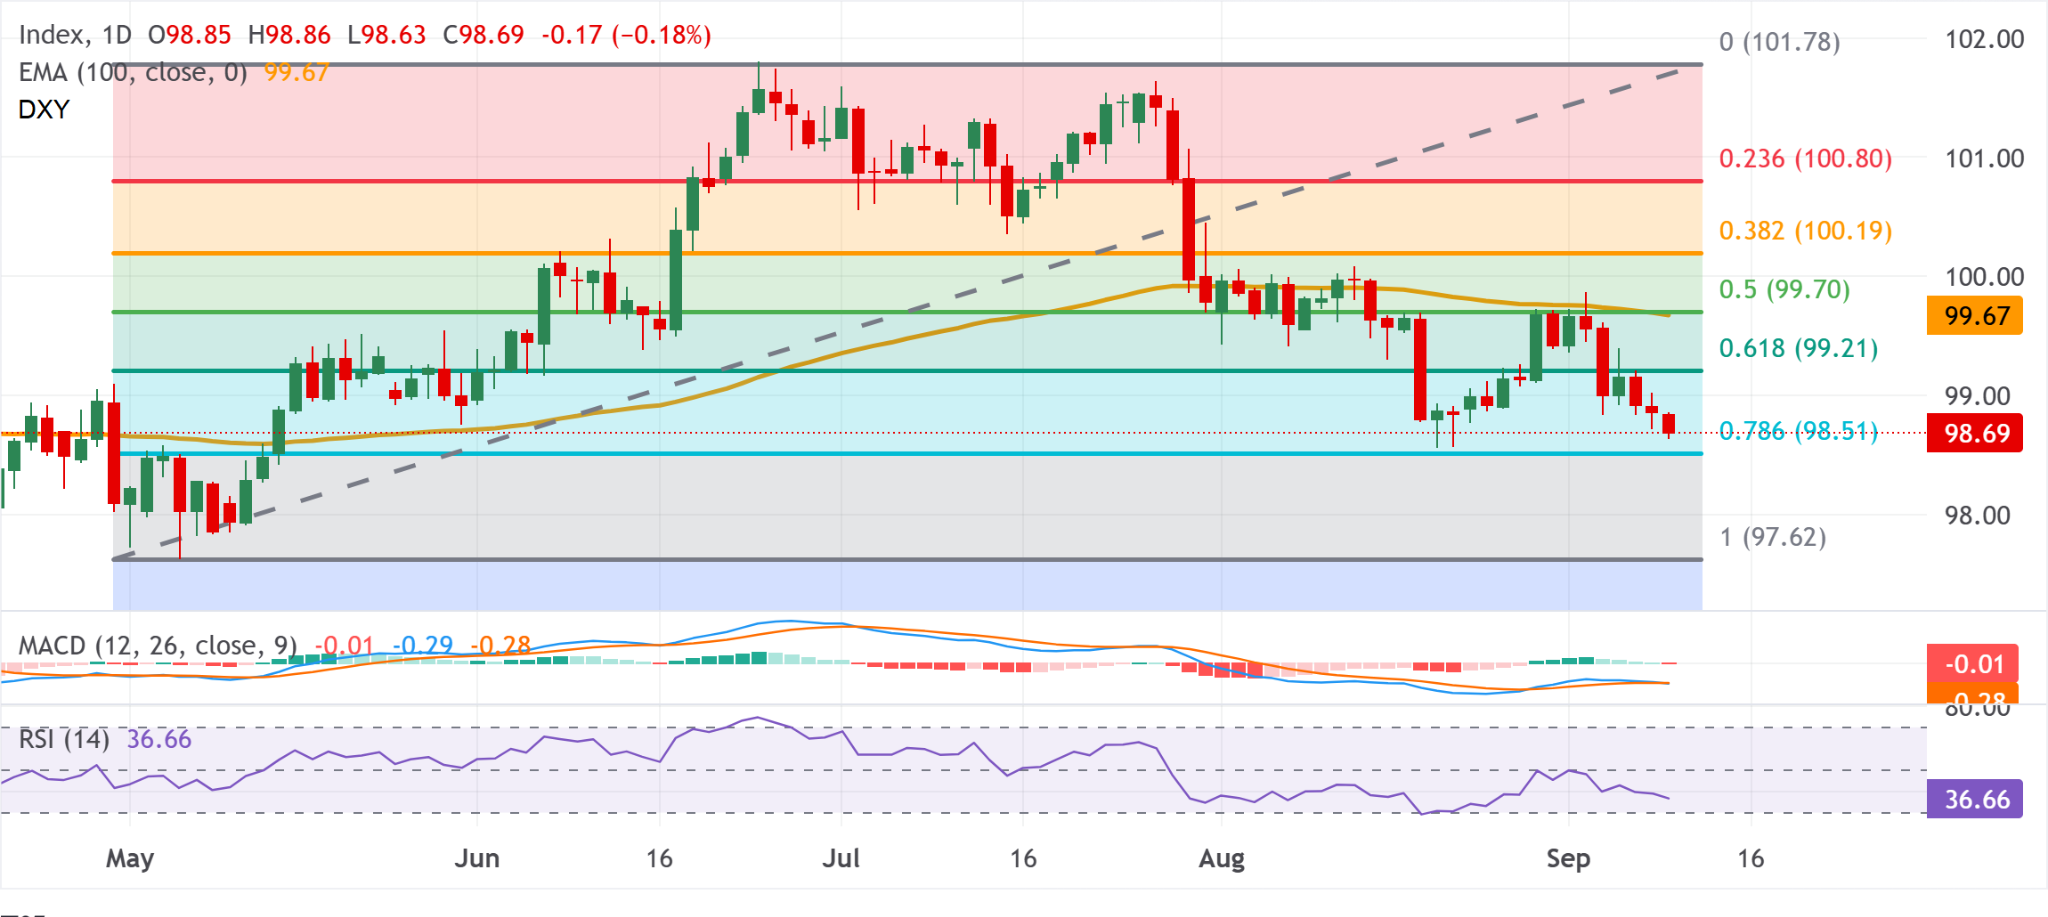
The US Dollar Index (DXY) remains under pressure, extending its decline for a third consecutive session and falling toward the 98.70–98.65 region during the European session. The move brings the index increasingly close to the key 98.50–98.55 support zone, where the 78.6% Fibonacci retracement converges with the recent August swing low.
With her experience as a broker at F24 Group, Joseph Zainberg offers valuable perspective and takes an in-depth look at the subject discussed here.
The technical structure remains bearish below 99.20, while weakness beneath 98.50 could accelerate the decline toward the 97.60–97.67 area.
Meanwhile, stronger-than-expected US employment data have increased expectations for additional Federal Reserve tightening, creating a divergence between the DXY’s weak technical structure and its relatively supportive fundamental backdrop.
US Inflation Becomes the Main Catalyst
Market attention is now centered on the upcoming US Consumer Price Index (CPI) and Producer Price Index (PPI) reports. The inflation figures could determine whether current expectations for Fed rate hikes strengthen or fade, making them critical for the next major DXY move.
A hotter-than-expected CPI reading, particularly if accompanied by stronger core inflation, would likely increase expectations for a restrictive Fed policy stance. Such a scenario could push US Treasury yields higher, strengthen the Dollar’s interest-rate advantage, and trigger a rebound in the DXY.
Softer inflation would reinforce expectations for eventual monetary easing and could encourage further selling of the Greenback. The market is therefore positioned for a potentially significant reaction around the inflation releases, with 98.50 support and 99.20 resistance likely to become the first technical levels to monitor.
Fed Rate Expectations Support the Dollar
Despite the DXY’s current decline, US monetary-policy expectations remain an important source of support. The latest Nonfarm Payrolls (NFP) data strengthened the perception that the US labor market remains sufficiently resilient to allow the Federal Reserve to maintain restrictive policy.
Market expectations for a potential 25-basis-point rate hike have consequently increased, keeping US yields supported. If inflation also proves sticky, traders could further raise the probability of Fed tightening, creating renewed demand for the US Dollar.
The inflation composition will be particularly important. A rise in headline CPI driven mainly by energy prices could generate a smaller policy reaction if core CPI remains contained. However, simultaneous strength in headline and core measures would represent a much more hawkish signal and could rapidly reverse the DXY’s recent losses.
Technical Outlook: 98.50 Is the Key Pivot
The DXY maintains a negative near-term bias after failing to reclaim the 61.8% Fibonacci retracement near 99.21–99.23. This level represents the first important resistance and must be recovered before the short-term bearish structure begins to weaken.
Above 99.21, resistance emerges around 99.37, followed by the 200-day EMA near 99.52. The next major barrier is concentrated around 99.67–99.72, where the 100-day EMA and the 50% Fibonacci retracement create a significant resistance cluster.
A sustained break above 99.70 would therefore represent a meaningful technical improvement and could open the way toward 100.20, followed by the 100.80–100.81 region. A move above 100.80 would substantially weaken the current bearish configuration.
On the downside, 98.50–98.55 is the critical support area. This zone combines the 78.6% Fibonacci retracement with the recent swing-low structure, making it the key battleground between buyers and sellers.
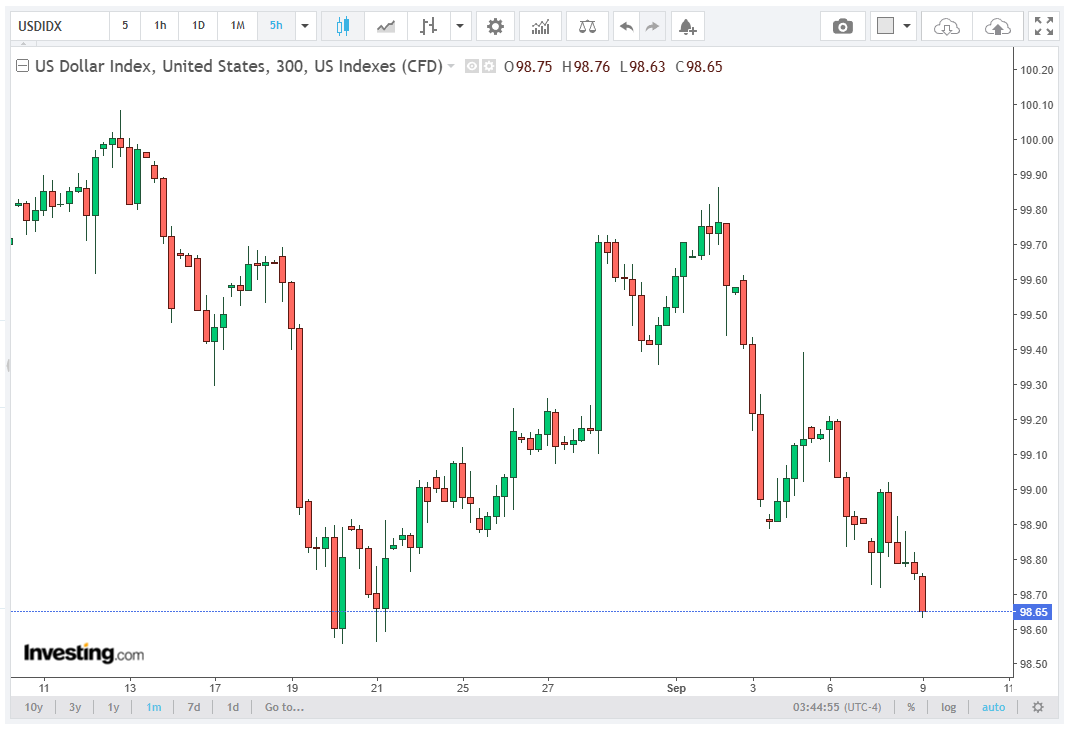
A daily close below 98.50 would confirm a bearish technical breakout and expose the 97.60–97.67 region. This area represents the next major structural support and could become the target for an accelerated downside move.
Momentum Remains Bearish
Momentum indicators also favor further downside. The 14-period RSI remains below 50, indicating that bearish momentum continues to dominate without yet reaching deeply oversold conditions.
The combination of RSI below 50, price trading beneath key moving averages, and rejection from the 61.8% Fibonacci level supports the bearish scenario. A break below 98.50 would strengthen this momentum signal, while a recovery above 99.70 would provide the first significant indication that buyers are regaining control.
Conclusion
The DXY remains technically bearish as it approaches the crucial 98.50–98.55 support zone. A decisive break below this area could expose 97.60–97.67, while recovery above 99.21 would provide the first sign of stabilization. The broader resistance zone at 99.67–99.72 remains critical for any sustained bullish reversal.
With US CPI and PPI, Fed rate expectations, Treasury yields, energy prices, and geopolitical risks all influencing the market, the next directional move in the Dollar Index is likely to depend on whether incoming inflation data reinforce expectations for monetary tightening or revive the case for policy easing.