

UK 10-year government bond yields climbed to 5.2501 percent recently, their highest level since the height of the Global Financial Crisis in 2008. The 30-year Gilt yield also surged to 5.8909 percent, a level not reached since March 1998.
Those are not abstract numbers for equity investors. Yields at those levels change the valuation math for every listed company on the London Stock Exchange, and their implications ripple across sectors in ways that are worth examining carefully.
The brand’s expert broker shares what Gammance sees as the most consequential effects of this Gilt yield move for investors with FTSE exposure.
Why Yields Are Rising This Sharply
Inflation is the proximate driver of the Gilt yield surge. Eurozone consumer prices rose to 3.3 percent in August from 2.9 percent in July, with energy inflation accelerating to 14.3 percent from 10.3 percent. UK inflation is following a similar trajectory, driven by the same oil price pressures tied to the ongoing US-Iran conflict and the sustained disruption to Strait of Hormuz shipping.
When inflation accelerates, bond markets demand higher yields to compensate for eroding real returns, pushing existing bond prices down and new-issue yields up. That dynamic has accelerated as each monthly inflation reading confirms that price pressures are not easing at the pace earlier central bank projections assumed.
The Bank of England’s rate policy is the other factor. With the ECB now expected to raise rates at its September meeting, the Bank of England faces renewed pressure to demonstrate equivalent commitment to inflation control.
Markets are pricing in a higher-for-longer rate environment across European central banks, and the Gilt market is reflecting that expectation by demanding yields not seen in a generation.
The Sectors Hit Hardest by High Gilt Yields
UK housebuilders are facing the most direct impact. Companies including Persimmon and Barratt have faced sustained pressure throughout 2026 as elevated mortgage rates suppress housing transaction volumes and new-build starts.
When the 30-year Gilt yield approaches 5.9 percent, mortgage rates tracking it push home purchase affordability out of reach for first-time buyers, directly reducing new-home demand and starter-home valuations. Utilities and real estate investment trusts are also in the firing line.
These sectors carry heavy debt loads, make long-duration capital investments, and distribute income to investors who compare the yield against what they could earn from government bonds.
At 5.25 percent on the 10-year Gilt, a utility or REIT needs to offer a meaningfully higher yield to attract capital, meaning it must either pay out a larger portion of earnings or accept a lower stock price that mechanically delivers the required yield.
Energy and Mining as the Counterweight
The FTSE 100’s composition provides a structural buffer that continental European indices do not have to the same degree. BP and Shell, two of the index’s largest components, are generating significantly higher revenues as Brent crude trades near $95 per barrel.
The oil price premium tied to the Iran conflict that is driving UK inflation higher is simultaneously driving energy company earnings higher. That inverse relationship between oil prices and most of the UK economy, and oil prices and energy company profitability, is the defining feature of the FTSE 100’s current sector dynamics.
Mining companies including BHP, Rio Tinto, and Anglo American provide a similar partial offset. Their revenues track commodity prices that also benefit from the inflationary environment, even as the broader domestic economy faces cost pressure.
Investors who understand this internal FTSE 100 hedge, energy and mining outperforming while rate-sensitive domestic names lag, are better positioned to navigate the Gilt yield environment.
BAE Systems and the Defense Premium
BAE Systems has been one of the FTSE 100’s more consistent performers in the current geopolitical environment. Defense sector demand has been rising across NATO member governments as the US-Iran conflict reinforces the case for maintaining and expanding military capabilities.
BAE’s position as a major UK and international defense contractor gives it revenue streams tied to government commitment rather than consumer willingness to spend, making its earnings relatively insulated from the household budget pressures driving weakness in consumer-facing sectors.
The juxtaposition between BAE’s performance and the housebuilders’ struggles encapsulates the FTSE 100’s current split personality.
International commodity and defense names are performing well because the macro environment favors their specific revenue drivers. The domestic consumer and property names are suffering from those same conditions.
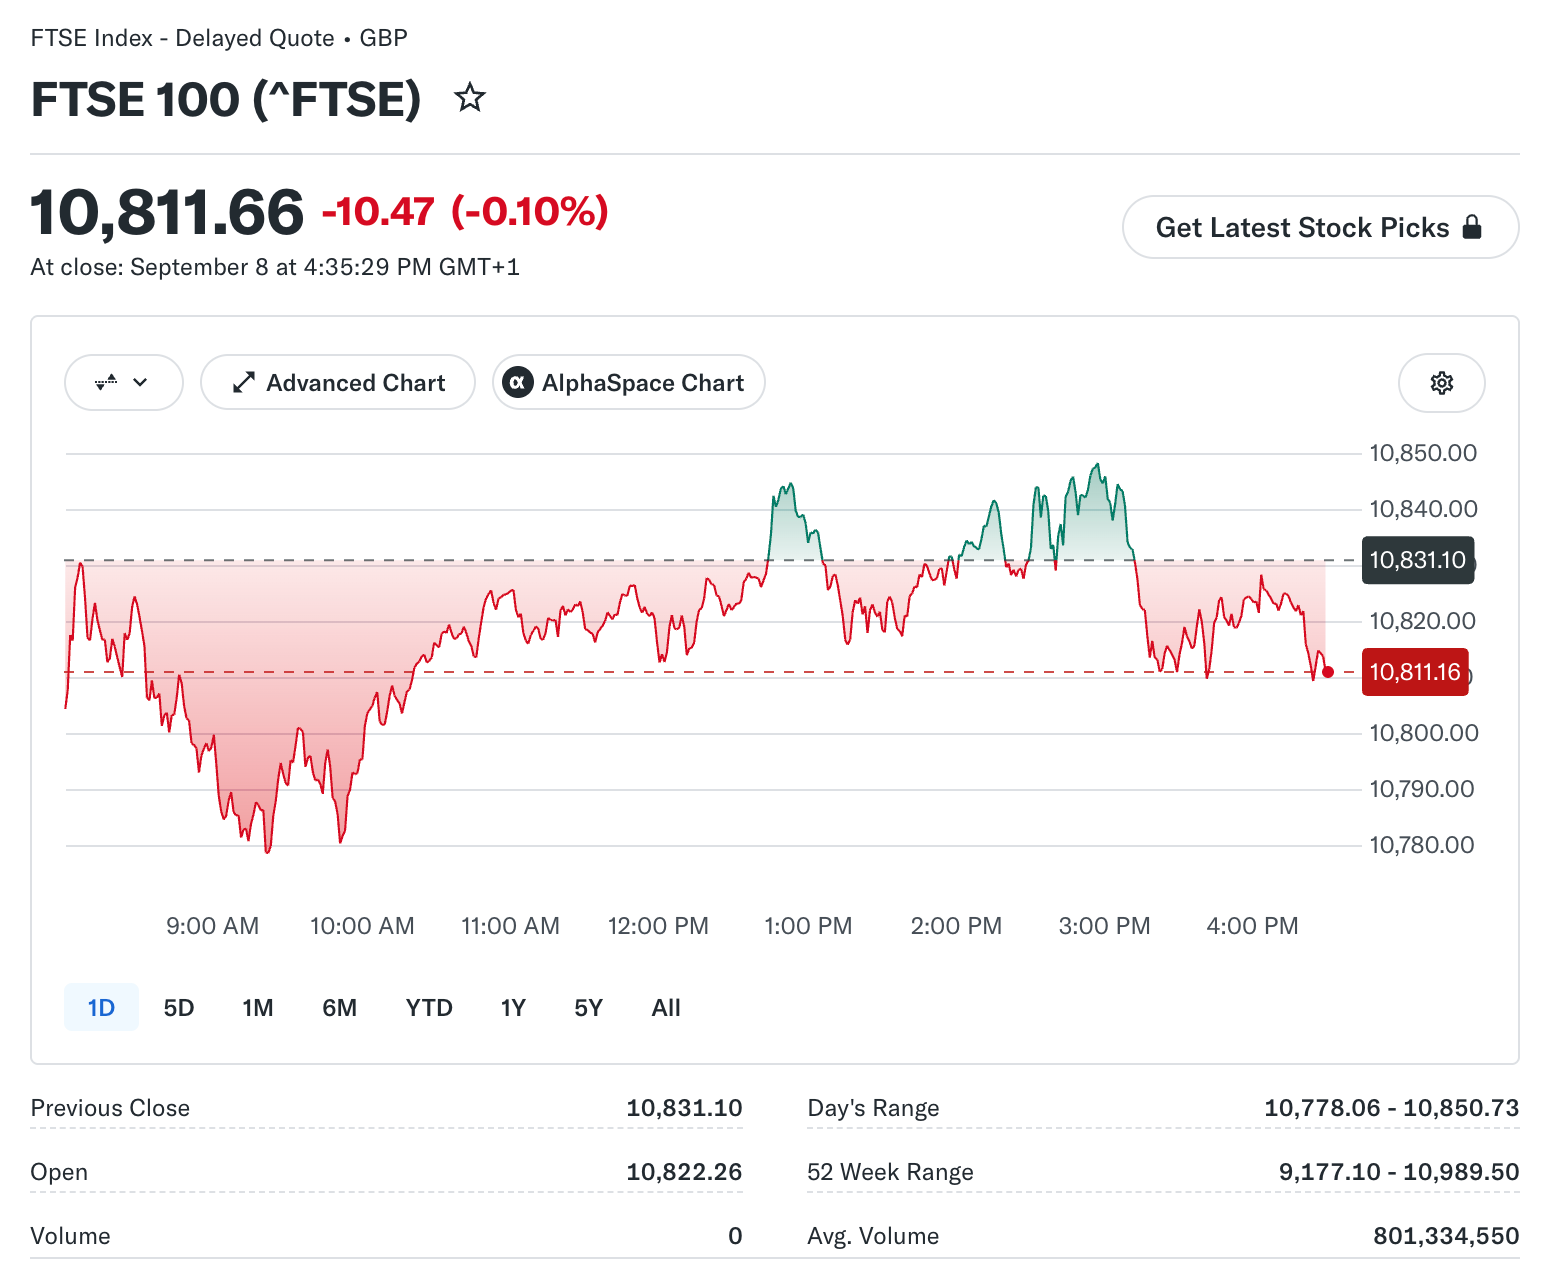
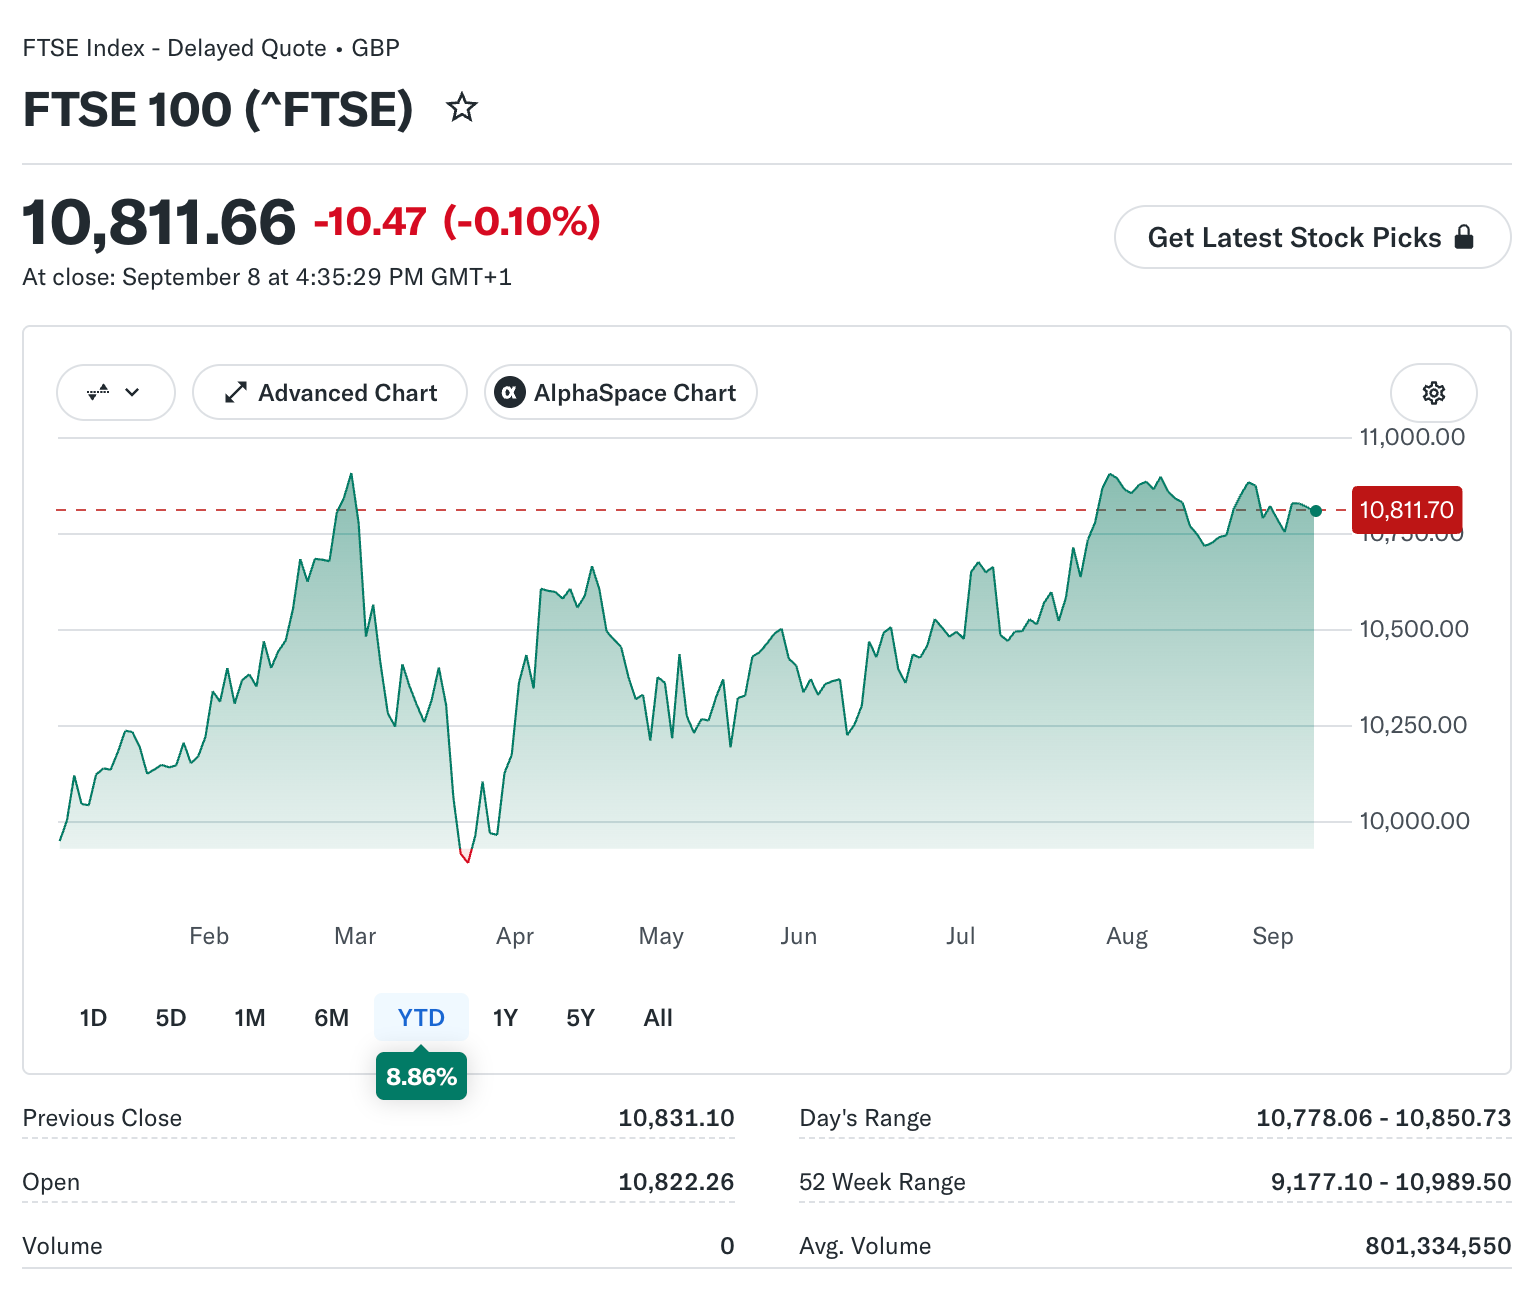
Understanding which side of that divide any given stock sits on is the most useful analytical framework for FTSE investors navigating the current Gilt yield environment. The index’s headline performance frequently understates the dispersion beneath it, with energy and defense names masking the severity of declines in housebuilders, utilities, and retail names most exposed to the interest rate transmission mechanism.