

Snowflake and Palantir were among the best-performing software stocks in the most recent trading week, recovering from significant losses accumulated in the first half of 2026. Salesforce also participated in the rebound.
The recovery in these names came as NVIDIA’s blockbuster quarter validated broad AI demand and lifted the entire technology stack, including software platforms that monetize AI data and analytics workloads. The brand’s senior financial advisor mentions that Gammance sees the software recovery as selective and thesis-dependent rather than a broad sector move.
Understanding which companies are recovering and why is more useful than tracking the category as a single block. The divergence within software is as instructive as the divergence between software and hardware in explaining how the AI investment cycle is distributing its rewards across the technology sector.
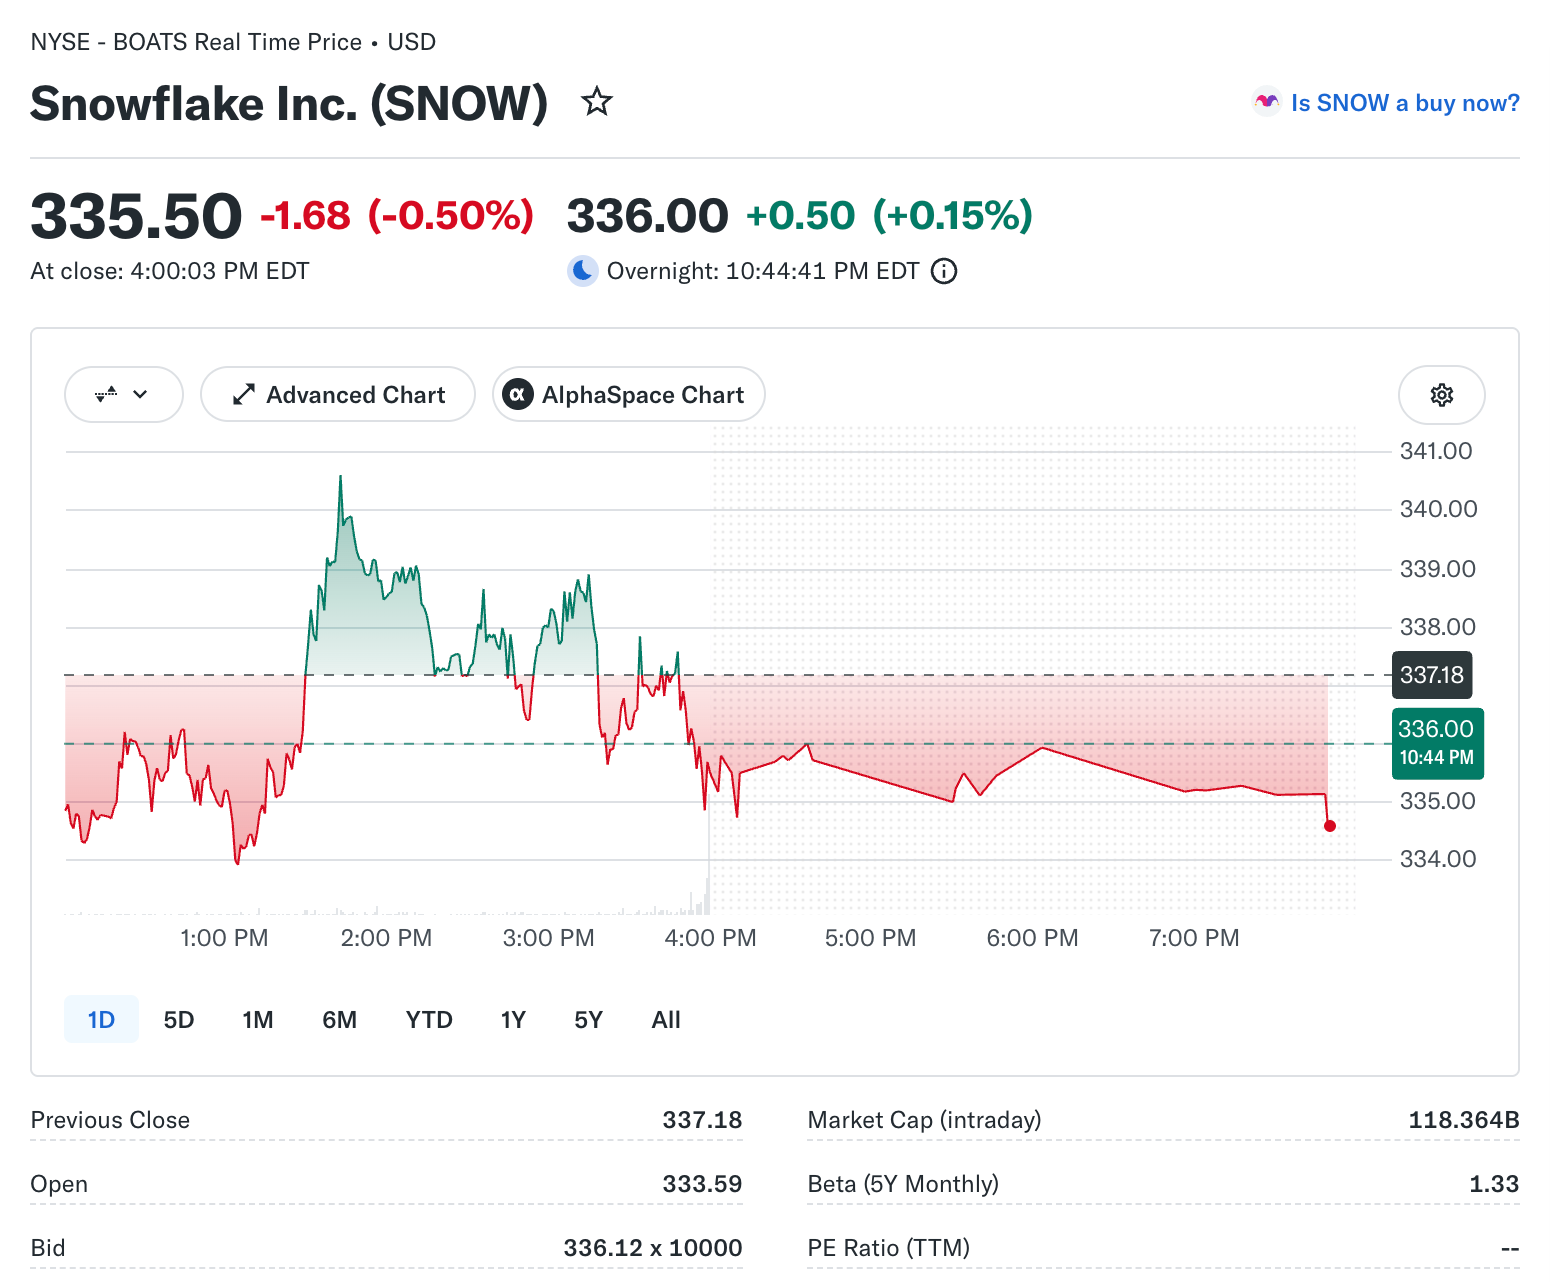
Snowflake’s Year in Context
Snowflake was up approximately 40 percent for the year heading into its most recent earnings release, recovering from sharp losses in early 2026.
That performance followed a period when the AI data cloud company was one of the hardest-hit names in enterprise software as investors questioned whether its revenue growth rate could sustain the premium valuation multiple the stock had commanded.
The subsequent recovery was driven by improving enterprise AI data platform spending and the realization that companies managing large AI workloads need specialized data warehousing and analytics infrastructure. Snowflake’s revenue guidance of approximately $1.48 billion and earnings per share of $0.45 for the most recent quarter reflected the analyst consensus heading into the release.
The market’s response to those expectations, combined with the positive sector sentiment from NVIDIA’s AI demand signal, created a constructive backdrop for Snowflake’s stock heading into its own reporting period.
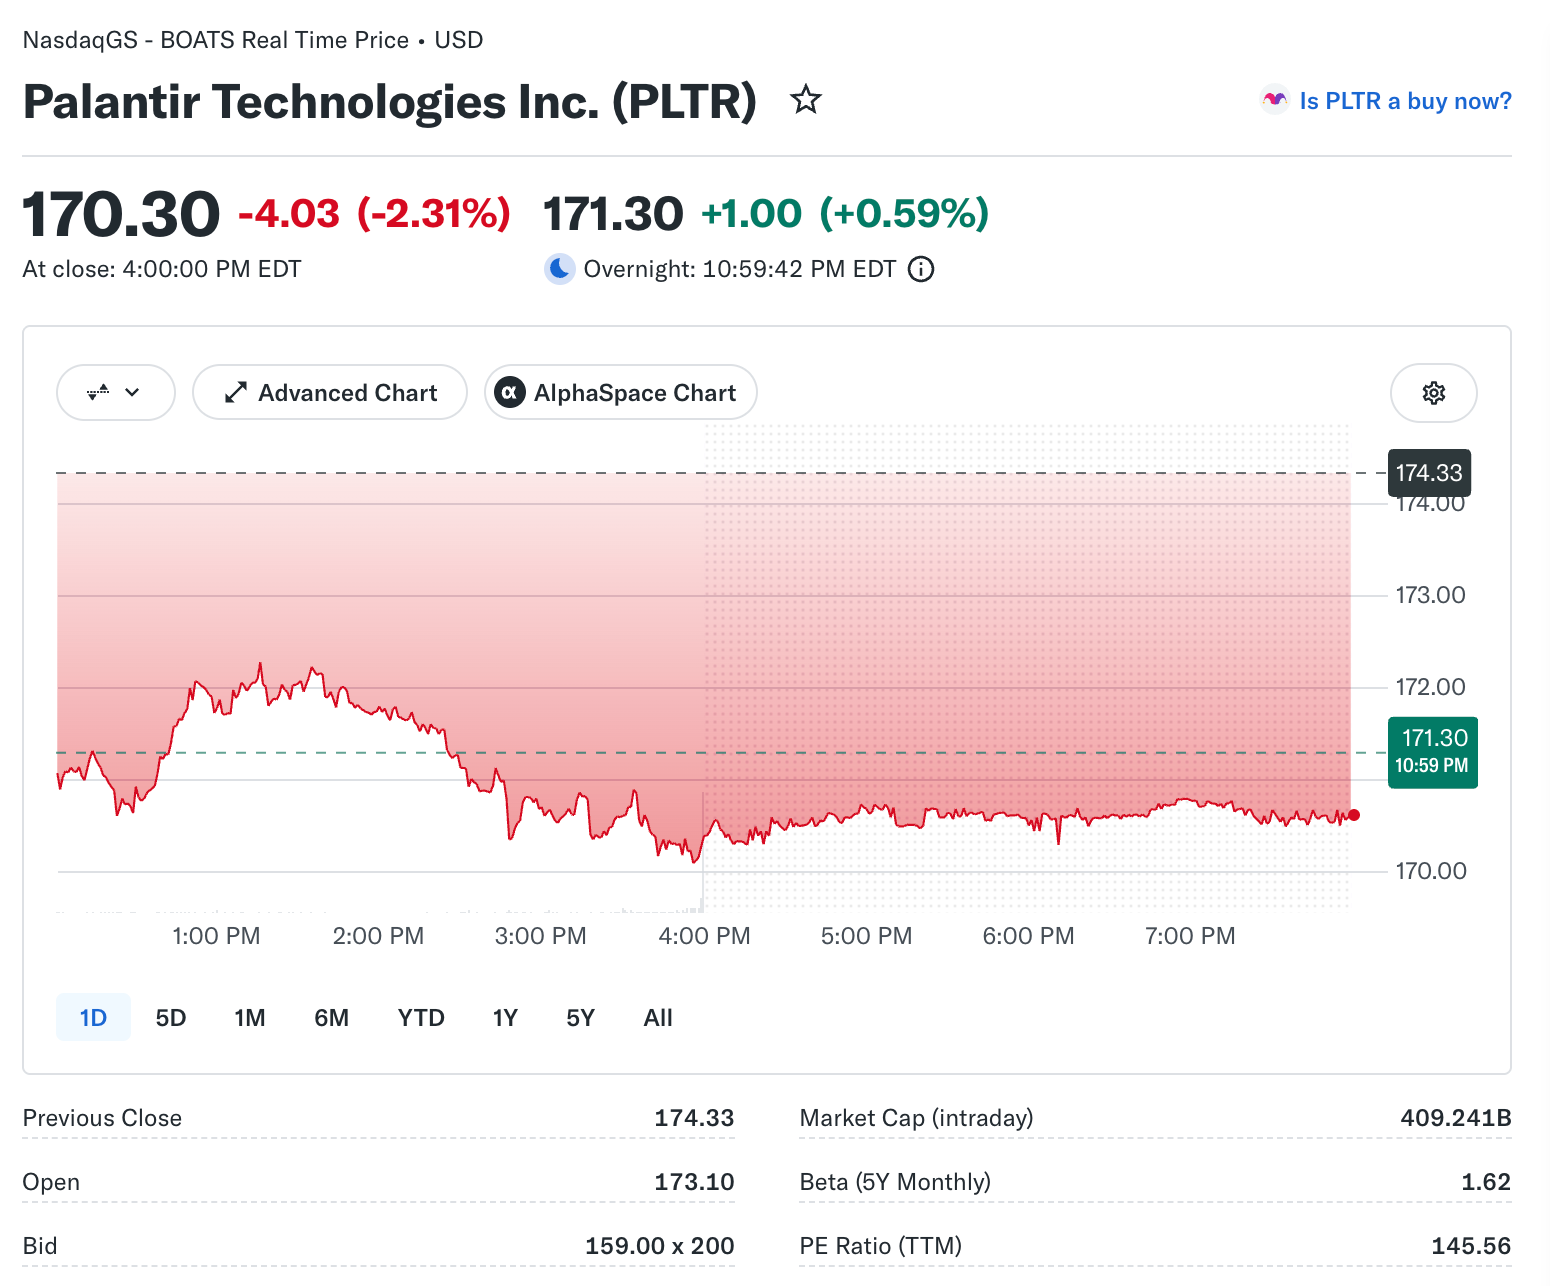
Palantir’s Different Path to Recovery
Palantir’s recovery has followed a different trajectory from Snowflake’s. Palantir sells AI-powered data analytics software primarily to government agencies and large enterprise customers.
Its revenue mix between government contracts and commercial clients has been shifting toward commercial, which carries higher growth potential but also more variability than the recurring nature of government contract revenue. Palantir’s AI tailwind comes from the same infrastructure buildout driving NVIDIA’s revenue surge.
More AI computing power generates more AI data, and more AI data requires better analytics tools to extract actionable insights. Palantir’s Artificial Intelligence Platform, known as AIP, has been gaining commercial traction as enterprises move from AI experimentation to AI deployment at operational scale.
Why the Software Recovery Is Selective
Not all software companies are participating equally in the recovery that Snowflake and Palantir are experiencing. The companies recovering most strongly share a specific characteristic: a credible, visible connection to AI workload monetization.
Snowflake’s data cloud processes the training data and inference results that AI models generate. Palantir’s platform turns those outputs into operational decisions. Both have a concrete revenue mechanism tied to AI deployment at scale.
Software companies without that AI connection have recovered more slowly or not at all. Legacy enterprise software in categories like HR management, procurement, or basic accounting has less obvious AI monetization to offer at the current stage of the technology cycle.
Investors rebuilding software exposure should screen for AI workload revenue specificity rather than treating the category as a broad recovery play.
How Hewlett Packard Enterprise Fits the Picture
Hewlett Packard Enterprise more than doubled in 2026, rising 119.3 percent to become the top performer on a list of significant tech earnings movers. The enterprise hardware maker’s performance reflects the same AI infrastructure spending wave driving NVIDIA.
As data centers upgrade to AI-capable configurations, HPE’s server, networking, and storage hardware is being purchased at rates that significantly exceed pre-AI baseline demand. HPE also rose 5.5 percent in premarket trading following Dell’s strong results, illustrating how AI infrastructure earnings reports create positive spillovers across the hardware supply chain.
Dell’s strong AI server order commentary lifted HPE as a direct competitor and beneficiary of the same enterprise spending cycle. The hardware recovery and the software selective recovery are two expressions of the same underlying demand driver, even if they are playing out at different velocities and valuations.
Positioning the Software Recovery Against the Rate Backdrop
The software recovery is occurring in an environment where Treasury yields are at multi-year highs, and the Federal Reserve is pricing a near-50 percent probability of a rate hike at its September meeting. Those yields apply mathematical pressure to software stock valuations that rely on long-duration earnings projections.
Companies like Snowflake and Palantir trade at multiples that imply years of continued high growth, and higher discount rates reduce the present value of those out-year earnings regardless of the quality of the underlying business momentum.
Investors rebuilding software exposure after the first-half selloff should treat the current rate environment as a persistent risk that can compress multiples even as fundamentals improve.
The optimal position captures the AI monetization upside through companies with near-term revenue evidence while sizing the position to survive additional valuation compression if the yield environment worsens further before it improves.