

There is a keen eye on Oracle Corporation (NYSE: ORCL) from those in the market with an interest in high-growth cloud infrastructure, particularly as derivatives traders put in place some aggressive positions before the company’s numbers are released.
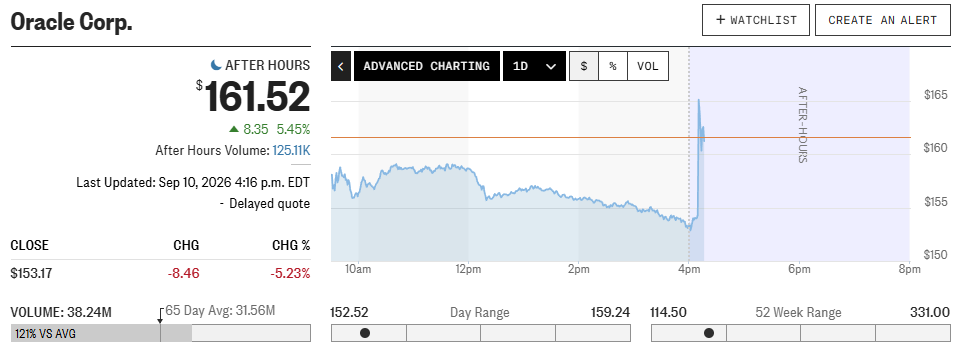
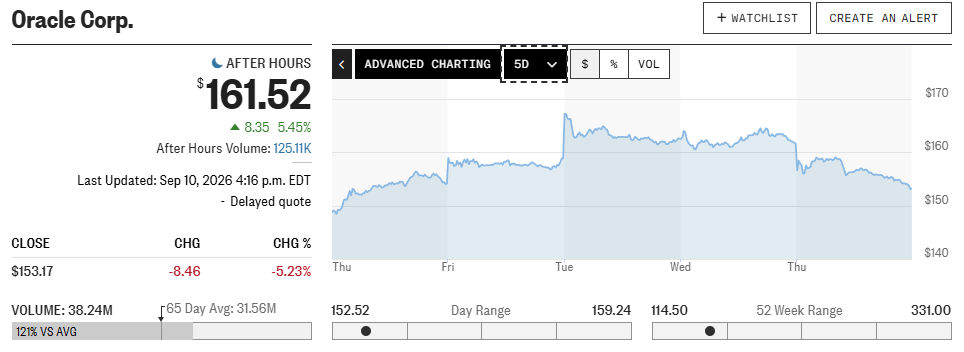
The picture is not uniform across the board; whereas the S&P 500 and Invesco QQQ Trust have set new records, the database pioneer has given back ground, down 17.83% for the year and 33.57% in the last twelve months to sit at about $158.62.
Yet even with that kind of pullback from earlier highs, one finds an odd skew in the options markets. Call contracts are priced up relative to puts, a sign of heavy speculative wagers on upside while institutional types argue over the sustainability of capital spending.
Then there is the matter of corporate governance and strategy when it comes to data center growth and financial leverage. An equity analyst with AchievementsAI put it plainly: for enterprise software to build value over time, you need to turn those enormous contractual backlogs into operating cash flow that can be sustained.
Oracle may have an unmatched performance obligation backlog, but among market participants there is no consensus on where the funding will come from to underwrite such an ambitious expansion plan.
Deconstructing The Massive Performance Obligation Backlog
The core bull thesis centers on Oracle’s staggering remaining performance obligations, which surged to $638 billion, representing an extraordinary 363% year-over-year expansion.
Within this backlog, approximately $75 billion is tied directly to prepaid or customer-supplied graphics processing unit arrangements, while cloud infrastructure revenues expanded 93% and multi-cloud database revenue surged 404%.
Furthermore, management guided quarterly revenue growth between 27% and 29%, with cloud revenue expected to climb 58% to 64% and non-GAAP earnings per share projected between $1.72 and $1.76. Global graphics processing unit utilization sits at an elite 97.5%, reflecting intense corporate demand for artificial intelligence computing capacity.
Analyzing Balance Sheet Pressures And Capital Expenditure Intensity
Conversely, bears point to mounting financial strain and negative cash generation as primary headwinds. Free cash flow registered at negative $23.69 billion, driven by aggressive data center construction and infrastructure commitments.
To fund projected capital expenditures reaching $70 billion, Oracle plans to raise approximately $40 billion in new debt and equity financing, including a $20 billion at-the-market equity program.
This capital-intensive strategy diverges sharply from software peers like Microsoft and Amazon, which comfortably fund their respective artificial intelligence infrastructure buildouts directly from operating cash flow rather than heavy debt reliance.
Evaluating Options Market Imbalances And Skew Dynamics
Options market mechanics heading into the earnings announcement have captured widespread attention across Wall Street research desks. Market specialists note an unusual market inversion where call options trade at higher implied volatilities than protective put contracts.
Implied volatility sits near 73, placing the equity among the top tier of S&P 500 volatility measures, with an expected single-session move priced at roughly 11%.
While this call-heavy skew suggests speculative momentum and aggressive positioning for upside execution, institutional strategists caution that structured product hedging and covered-call selling often distort retail sentiment readings.
Comparing Market Valuations And Competitive Positioning
Evaluating Oracle’s valuation requires examining how the software leader stacks up against major cloud competitors. The equity trades at approximately 28 times trailing earnings and roughly 20 times projected fiscal year earnings, presenting a premium multiple justified by an anticipated 18% earnings growth trajectory.
By comparison, major cloud rivals manage enormous commercial backlogs while maintaining robust operating margins and positive cash generation.
The central competitive question remains whether Oracle can successfully protect its 30% to 40% infrastructure operating margins while absorbing the massive power, cooling, and networking expenses required to maintain its market share.
Analyst Consensus Ratings And Wall Street Price Targets
Despite recent downward price pressure, institutional sentiment remains overwhelmingly constructive across major financial brokerages. A total of 36 analysts maintain Buy ratings, supported by 7 Hold ratings and only 1 Sell rating, yielding a consensus 12-month price target of $241.43.
This consensus target implies significant double-digit upside from current trading levels, reflecting confidence that execution on the massive backlog will ultimately override short-term balance sheet anxieties.
Assessing Macroeconomic Vulnerabilities And Enterprise Spending Trends
It is not only a matter of corporate metrics; the wider macroeconomic climate has a hand in dictating enterprise software adoption. The pace at which clients are willing to put their name to multi-year cloud agreements is directly affected by things like shifting interest rates and the ebb and flow of IT budgets.
There is no shortage of demand for specialized computing infrastructure, yet one can expect some friction in conversion times as economic headwinds set in. For institutional allocators, it is imperative to keep a close watch on the interplay between macro changes and leveraged balance sheets over the course of long capital expenditure cycles.