

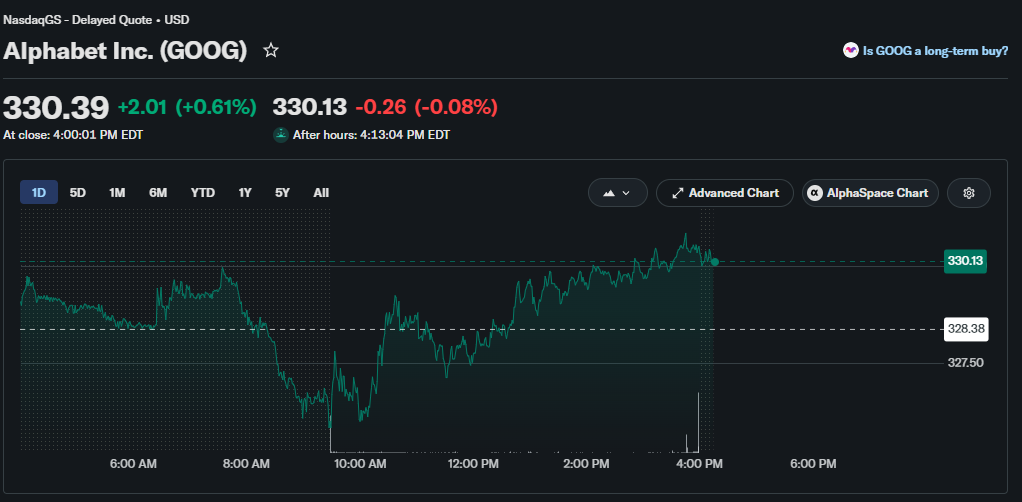
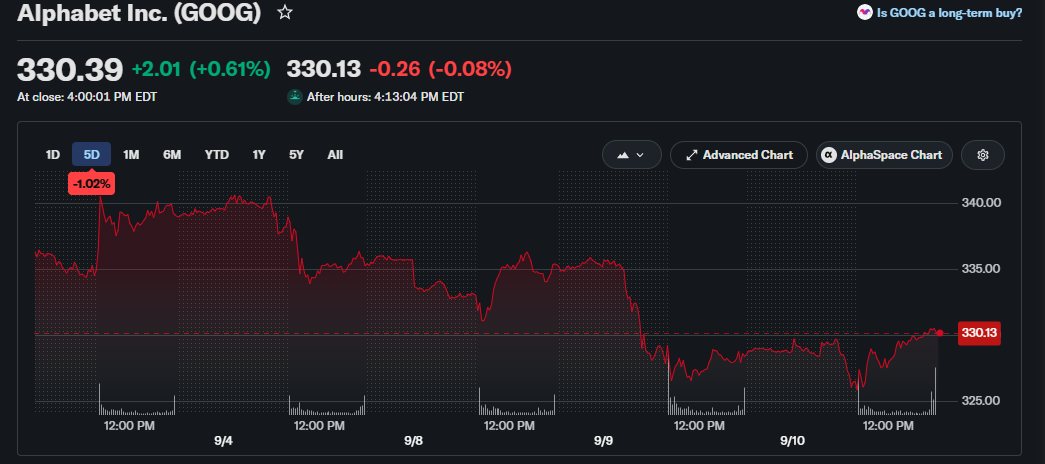
There is close attention being paid by equities in the global technology and hedge fund space to the latest regulatory disclosures from billionaire Bill Ackman. The filings put out by Pershing Square show that the fund has made a clean break with its multi-class holding in Alphabet Inc. (NASDAQ: GOOGL), liquidating it in full.
In one move, they have also put together a $934 million position in Netflix Inc. (NASDAQ: NFLX) amounting to 13.08 million shares.
Such a sweeping change of portfolio is among the more significant strategic maneuvers the well-known manager has put in place in some time, and it has set off no small amount of discussion on Wall Street over where artificial intelligence spending is headed in comparison to more seasoned cash-flow producers.
To strike the right note between putting capital back into technology and allocating it with discipline takes a certain kind of foresight. As one researcher at AchievementsAI would point out, the enterprise value in cloud computing and digital media is predicated on knowing when an infrastructure contest has run its course and become a high-margin cash cow.
While walking away from a pre-eminent AI name like Alphabet may come as a shock to some, the thinking behind it is sound, having to do with structural maturity and the demands on capital.
Revisiting Past History And Strategic Shifts In Streaming
The decision to re-enter the streaming giant marks a fascinating reversal for the billionaire investor. Pershing Square initially acquired a major stake in the streaming pioneer years ago, only to exit the position abruptly following a disappointing quarterly report involving subscriber contractions, resulting in a substantial realized loss.
Returning to the equity four years later signals a profound evolution in the fund’s perspective on the competitive landscape. Management commentary accompanying the recent portfolio update asserts that the enterprise has effectively secured victory in the grueling streaming wars, achieving sustainable operating leverage while rivals struggle with profitability.
Evaluating Alphabet And The Escalating Costs Of Artificial Intelligence Infrastructure
While the streaming leader stabilized its financial profile, the decision to divest from Alphabet highlights growing concerns over astronomical capital expenditures. During the most recent quarter, Alphabet posted impressive revenue growth, driven largely by an 82% surge in Google Cloud revenue reaching $24.8 billion, alongside total quarterly sales of $119.8 billion.
However, this top-line acceleration requires immense financial backing. Alphabet raised its capital expenditure forecast to a staggering range between $195 billion and $205 billion, pushing quarterly free cash flow into negative territory at negative $5.9 billion.
This staggering cash burn forces investors to weigh whether the immense revenue gains justify the unprecedented capital outlay required to maintain leadership in artificial intelligence infrastructure.
Contrasting Business Models And Free Cash Flow Profiles
The underlying divergence between the two corporate titans lies in their respective lifecycle stages and capital intensity. Alphabet remains locked in an expensive, high-stakes arms race to dominate next-generation computing infrastructure and proprietary tensor processing units.
Conversely, the streaming leader has passed its most aggressive content land grab and infrastructure spending phase. With projected full-year sales ranging between $51 billion and $51.4 billion alongside an impressive operating margin of 31.5%, the business can now focus on expanding advertising tiers, optimizing pricing models, and integrating live programming.
Broader Portfolio Reallocations Across The Hedge Fund Landscape
Beyond the headline-grabbing pivot between cloud computing and entertainment, the fund’s regulatory filing revealed multiple new equity positions. Alongside the streaming investment, Pershing Square initiated stakes in prominent financial and healthcare enterprises, including Visa, Mastercard, S&P Global, Intercontinental Exchange, and Alcon.
These adjustments demonstrate a broader thematic shift toward high-quality, fee-generating businesses with predictable cash flows, signaling a defensive posture against macroeconomic volatility and inflated technology valuations.
Assessing Long-Term Risks In The Digital Entertainment Ecosystem
Despite the renewed confidence in the streaming leader, significant risks remain embedded within the digital entertainment sector. The enterprise faces relentless competition for consumer attention from social media platforms, short-form video applications, and traditional gaming networks.
Furthermore, while the advertising-supported subscription tier is expanding rapidly, monetization metrics have occasionally lagged initial Wall Street expectations. Acknowledging these persistent vulnerabilities ensures that institutional allocators maintain realistic projections regarding subscriber growth velocity and long-term retention rates.
Investment Horizons and Market Highlights
There is a basic tenet of institutional investing that comes to the fore when one examines this particular portfolio rotation. It is incumbent on market participants to put aside headline revenue figures and assess the actual capital outlay needed to keep an edge over the competition.
With technology cycles in flux, the way an institutional portfolio is constructed will have lasting consequences for performance in whatever market conditions lie ahead. The key is to tell apart companies that are locked in expensive infrastructure battles from ones that have the luxury of mature operational efficiency.