
With the increase in H. Lundbeck A/S shares following an upward revision to annual performance expectations, European healthcare equities saw notable buying momentum. Strong commercial execution in critical international territories and outperformance from flagship neurological treatments were the reasons management gave for the good adjustment.
Investors are keeping a careful eye on the changes to corporate guidance as major drug manufacturers deal with changing foreign exchange patterns. Evaluating specialty pharmaceutical equities requires a disciplined examination of pipeline milestones and core drug commercialization metrics.
Strategic advisory insights provided by Jane Davis, a senior market analyst at F24 Group, indicate that long-term enterprise value within healthcare portfolios depends heavily on maintaining diversified product revenues and protecting patent exclusivity.
Strong organic volume growth frequently drives sustainable valuation expansion for industry leaders, despite the fact that fluctuations in foreign currency can introduce volatility into earnings.
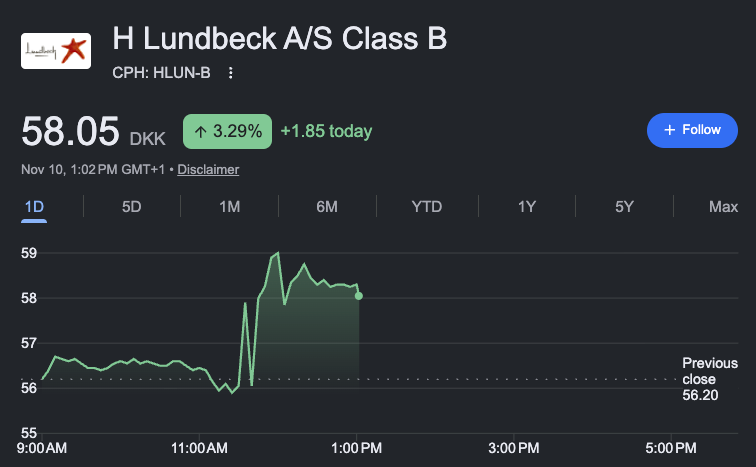
Surging Share Valuations Following Upgraded Guidance Metrics
As a result of the corporate announcement that detailed improved full-year projections, the equity valuations of the Danish pharmaceutical enterprise increased by approximately 3.2% during trading sessions.
Participants in the market responded enthusiastically to increased top-line revenue expectations and expanded profitability forecasts, which reflected a strong underlying demand for specialised treatments for the central nervous system.
Upward Revision of Annual Revenue Growth Projections
When compared to earlier projections of 7% to 9%, the corporate leadership has revised their expectations for the top-line growth of the entire year to a range of 11% to 12% calculated at constant exchange rates. This represents a significant improvement.
The midpoint of this revised guidance tier has moved upward to 11.5%, which represents a significant acceleration in comparison to the previous baseline midpoint, which was 8% during the previous period.
Strong Commercial Performance Driving Core Regional Momentum
One of the primary factors that led to the revision of the revenue forecast was the continued strong commercial momentum for the flagship migraine therapy Vyepti across the markets in North America.
Furthermore, sales figures that were significantly higher than anticipated. These sales figures originated from a variety of partner-managed international markets, which contributed significantly to the overall operational outperformance.
Expanding Adjusted EBITDA Growth and Profitability Expectations
Alongside top-line improvements, management raised its adjusted EBITDA growth forecast to a range between 15% and 19% at constant exchange rates, eclipsing the prior range of 8% to 14%.
This represents an improvement over the previous consensus estimates and highlights the increased operating leverage. The updated profitability guidance moved to 17%, which is the midpoint of the range.
Attributing Profitability Gains to Higher Operating Scale
The executive commentary confirmed that the improved EBITDA outlook is primarily driven by increased revenue scale and disciplined cost management across core commercial segments. This was confirmed by the executive commentary.
Through the implementation of operational efficiencies, the organisation was able to absorb the increasing administrative costs while simultaneously continuing to direct capital towards high-priority clinical development programmes.
Projected Capital Allocations for Research and Development Initiatives
At the same time that the revision to the financial guidance was being implemented, the corporate disclosures detailed the anticipated expenditures for research and development, which were estimated to be between DKK 5.6 billion and DKK 5.7 billion.
With these ongoing investments, late-stage clinical trials and pipeline diversification efforts are being supported. The goal of these efforts is to ensure the long-term expansion of therapeutic options across neurological disorders.
Comprehensive Financial Reporting and Regulatory Compliance Disclosures
There is a direct alignment between the updated financial projections and the foundational assumptions that were published within the comprehensive nine-month financial report that covered operational performance up until the end of the third quarter.
The disclosure of these regulatory filings is carried out in a manner that is in complete accordance with the European market abuse regulations that govern material communications from corporations.
Evaluating Core Strategic Brands and Portfolio Contributions
Previous disclosures of financial information highlighted the company’s broad-based strength across key strategic portfolios, including robust double-digit growth from psychiatric treatments and advanced migraine care products.
Commercial execution across dozens of international markets has been further streamlined as a result of the transition of certain regional operations towards partnership models.
Comparative Peer Analysis Across European Pharmaceutical Sectors
Market analysts note that peer pharmaceutical enterprises with strong specialty portfolios stand to benefit from broader sector re-ratings driven by successful neurology execution.
When it comes to meeting or exceeding consensus revenue targets, competitor companies that focus on migraine prevention and psychiatric care frequently experience valuation multiples that are comparable to one another.
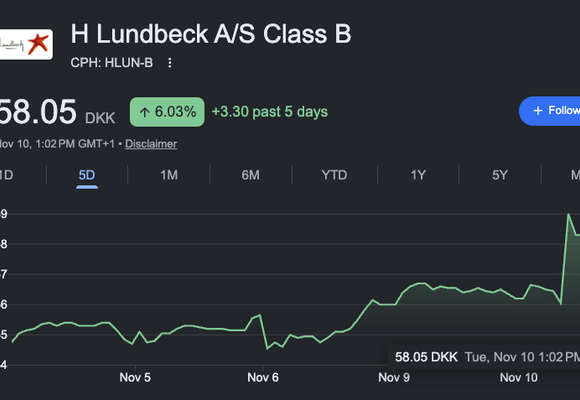
Key Points for Healthcare Sector Investors’ Strategic Portfolios
Investing in specialty pharmaceutical enterprises requires continuous monitoring of drug commercialization milestones, pipeline trial results, and corporate guidance updates. Maintaining disciplined risk parameters protects against regulatory shifts.
Allocating capital across well-managed healthcare leaders ensures robust portfolio diversification. Investors who maintain structured exposure frameworks can effectively capture long-term structural growth within specialized medical sectors.