

Every major technology company building AI infrastructure is running into the same wall. The power grid was not designed to accommodate the energy appetite of modern data centers, and the queue for new grid connections runs years long in many US markets.
That gap between what hyperscalers need and what existing infrastructure can deliver has turned energy supply into one of the most consequential strategic problems in technology. Bloom Energy identified this gap early and positioned itself to fill it.
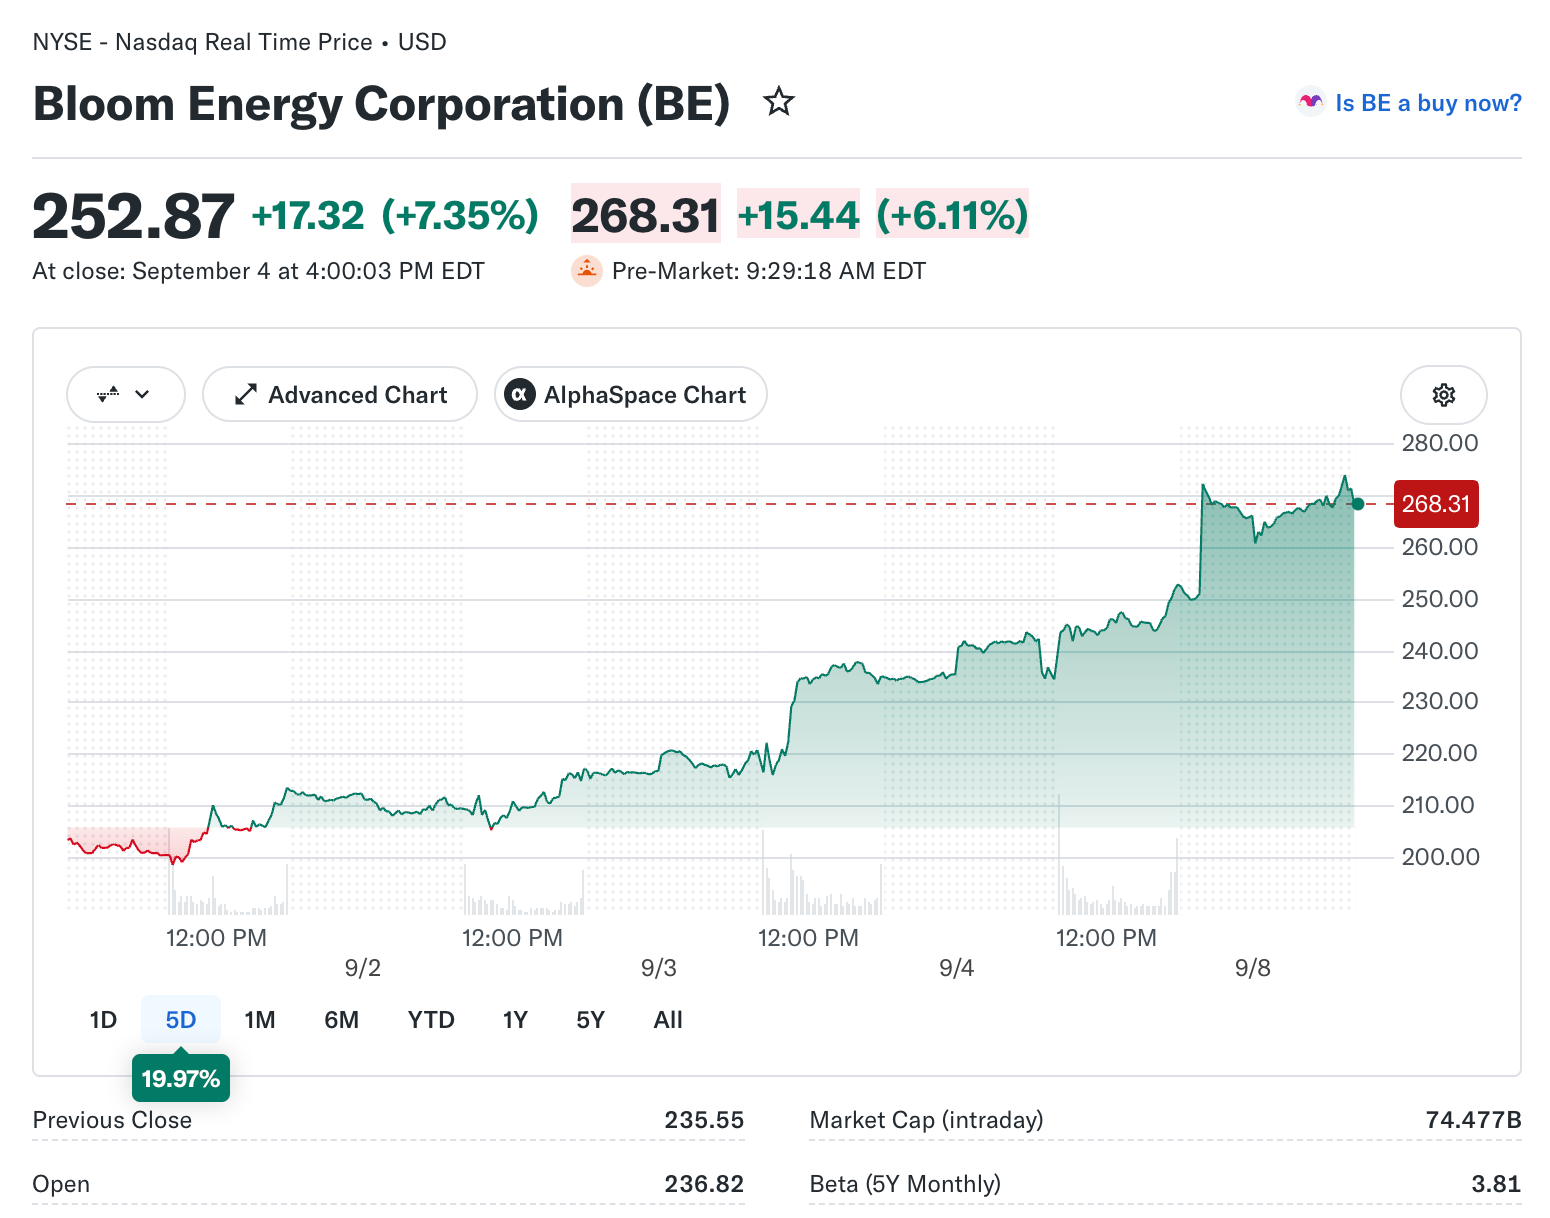
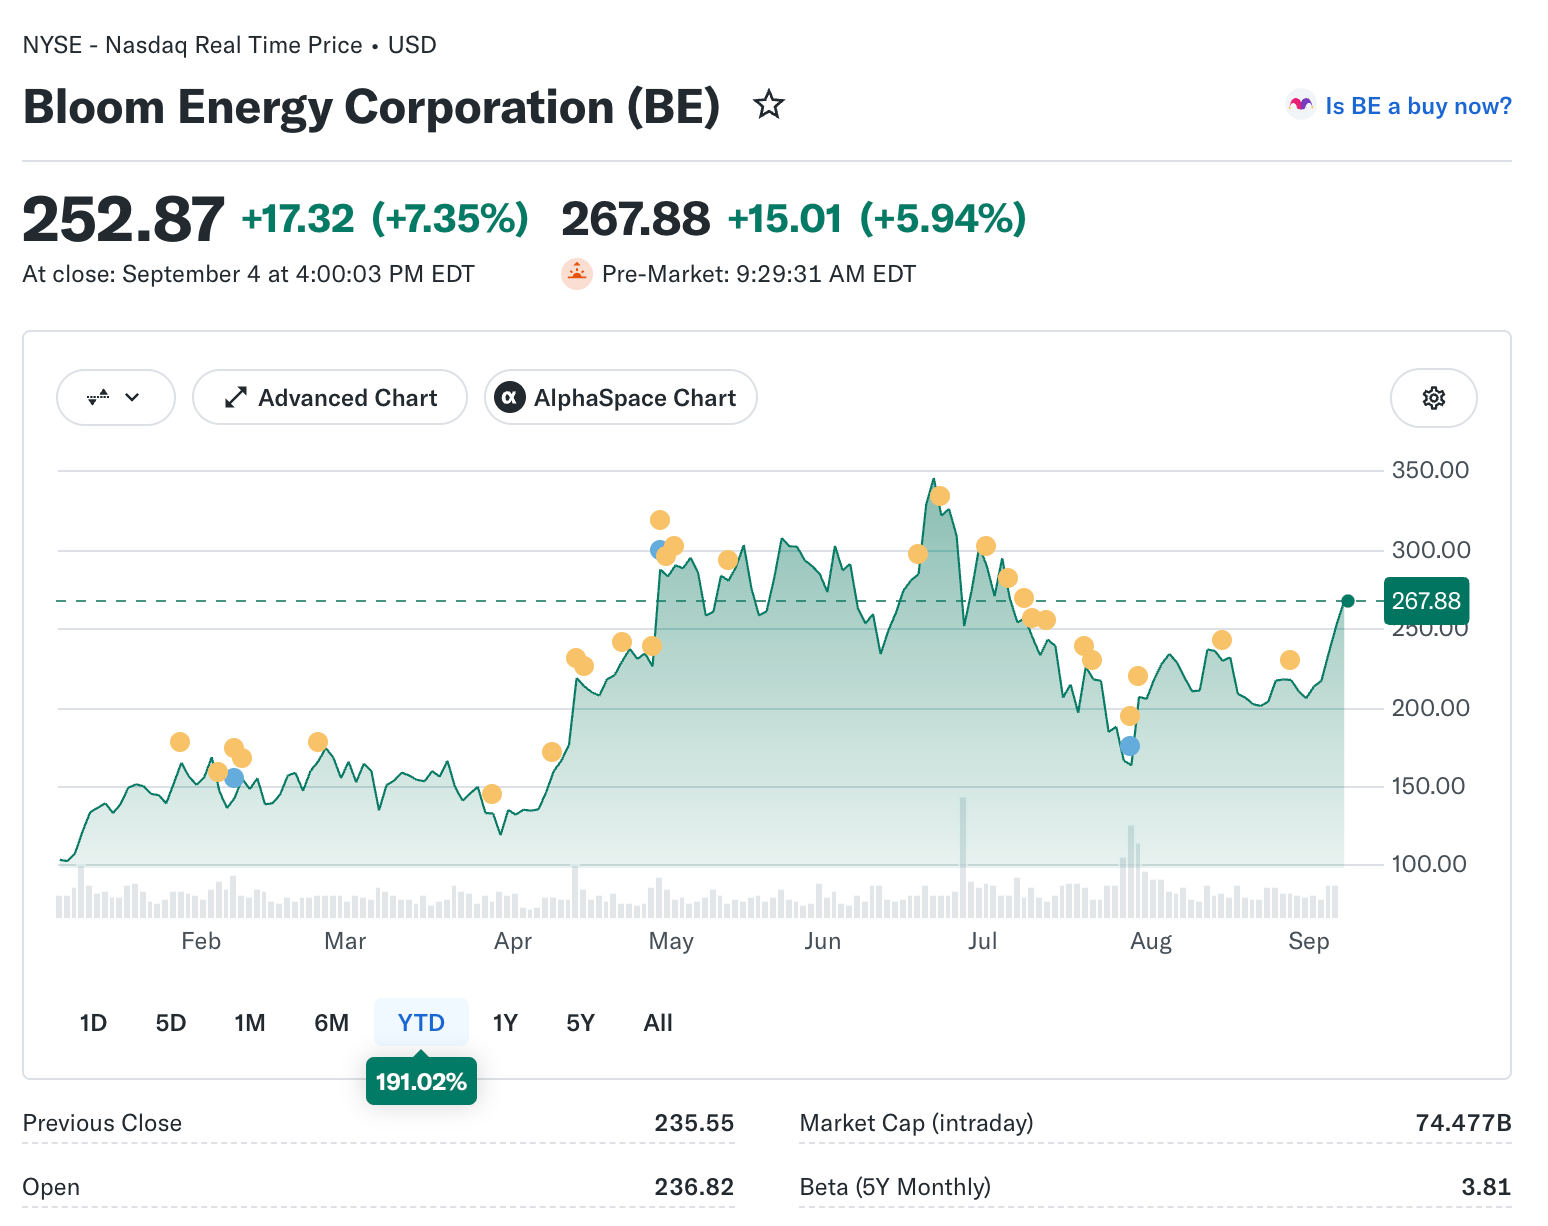
A lead financial analyst at Chilli Markets discusses why Bloom Energy’s 134 percent gain in 2026 is not a momentum story driven by retail enthusiasm. It is a fundamental repricing of a business whose technology addresses a bottleneck that the largest technology companies in the world cannot work around.
The Technology Behind the Stock Move
Bloom Energy builds stationary power systems that run on solid oxide fuel cell technology. These units sit on site at a customer’s facility and generate electricity directly, without drawing from the local utility network. The fuel source can be natural gas, biogas, or hydrogen, which gives customers flexibility in how they manage their energy supply and emissions profile.
The practical advantage of this approach is speed of deployment. A conventional grid connection for a large data center project can take several years to secure and complete. Bloom’s systems can be ordered, delivered, and generate power within weeks. For a hyperscaler trying to bring computing capacity online quickly, that difference in timeline is commercially significant.
What Oracle Committed and Why It Matters
Earlier this year, Oracle formalized a large-scale purchasing arrangement with Bloom Energy that changed the financial narrative around the stock. The agreement covers a substantial volume of Bloom’s fuel cell output earmarked for Oracle’s US data center expansion, including its Project Jupiter campus in New Mexico, where Bloom’s systems will serve as the primary power source for the facility.
The financial consequence of that commitment was an upward revision to Bloom’s full-year revenue guidance. Management lifted the 2026 outlook to between $3.40 billion and $3.80 billion, a figure that represents better than 50 percent growth over the prior year’s $2.02 billion result.
The Quarterly Numbers That Backed It Up
The Oracle announcement would carry less weight if Bloom’s operating results were not supporting the narrative. They are. Revenue in the most recent quarter came in near $751 million, a figure that roughly doubled the comparable period from a year earlier.
Profitability has also arrived. Net income exceeded $70 million in the quarter, compared with a loss in the same period twelve months prior. That move from loss to profit is the kind of inflection that institutional investors monitor closely, because it changes the quality of the growth story.
The contracted backlog is the figure that most directly quantifies forward visibility. Total backlog across product and service commitments sits near $20 billion, with the product component growing roughly 2.5 times year over year. A company with that volume of committed future revenue is not dependent on continuous new order wins to sustain its trajectory.
The Valuation Question Investors Cannot Ignore
A stock that has more than doubled in a year tends to carry a valuation that demands scrutiny, and Bloom Energy is no exception. The shares have been trading above where the analyst consensus views fair value, which is a signal that the market is pricing in execution outcomes that have not yet been demonstrated.
Multiples in the range of 20 times forward revenue do not leave much room for deployment delays, customer concentration concerns, or manufacturing capacity constraints. The Oracle relationship is the central support for the current valuation.
If those deployments proceed on schedule and the contracted volume translates into recognized revenue within the expected timeframe, the financial model that justifies the current price holds together.
If deployment slips by several quarters, or if Oracle’s own data center buildout timeline shifts, the revenue recognition delay could expose the stock to a meaningful correction from its current elevated multiple.
Where the Long-Term Argument Gets Complicated
Natural gas is the primary feedstock for most of Bloom’s current commercial installations. That creates a dependency on fossil fuel at a time when regulatory pressure on carbon emissions is intensifying.
Bloom has been developing hydrogen compatibility for its systems, which would address the emissions concern, but commercial hydrogen supply chains are not yet mature enough to support that transition at scale.
The broader competitive picture is also evolving. Grid modernization programs are accelerating, battery storage costs are falling, and small modular nuclear reactors are advancing through regulatory approval processes.
None of these alternatives currently matches Bloom’s speed-to-power advantage, but the window in which that advantage is decisive will compress over time. Investors building a long-term position need a view on whether the company can accumulate enough customer relationships and manufacturing scale during this window to remain competitive once the grid catches up.