

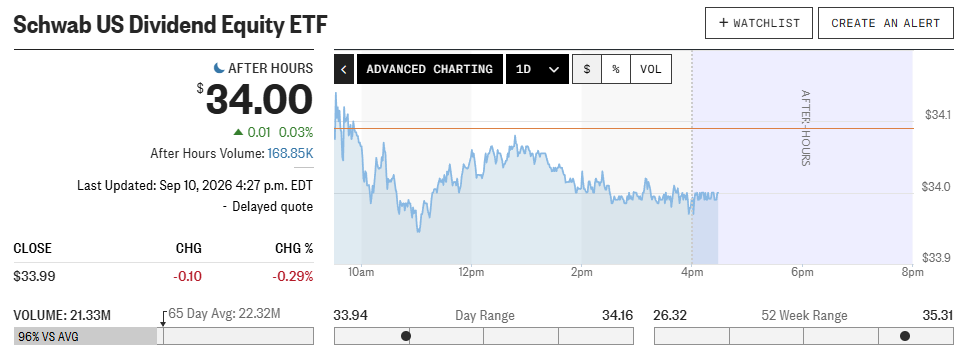
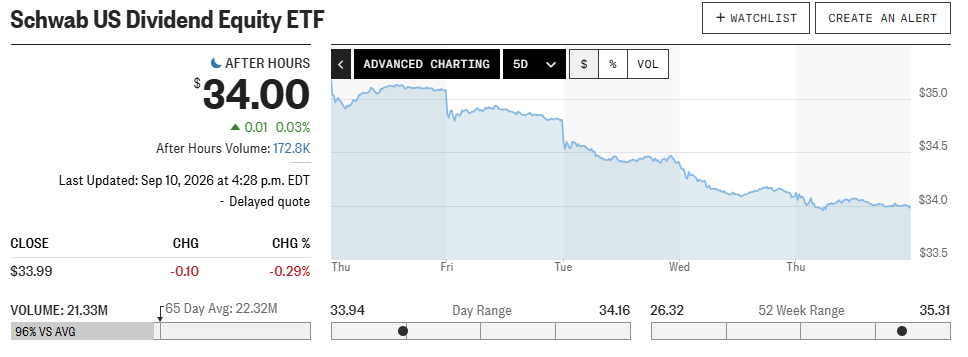
The Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) is considered to be one of the most successful dividend stocks in the United States. With a return of 30.27% in the most recent year and a gain of 240.51% over the course of the previous decade, the entity has demonstrated strong historical performance and currently possesses net assets estimated to be worth $111.42 billion.
However, if an income portfolio is limited to domestic equities, then a sizeable portion of the opportunities to receive dividends from companies around the world are not taken advantage of.
Developed and emerging markets outside of the United States are subject to the same quality and financial health screening standards, and Schwab has introduced a global companion fund that applies these standards.
To successfully navigate global equity allocations, it is necessary to practice disciplined portfolio diversification and strategic currency risk management. Both of these practices are necessary.
An equity analyst at AchievementsAI pointed out that the long-term enterprise value of international portfolios is heavily dependent on the ability to capture stable non-domestic cash flows while simultaneously managing the volatility of foreign exchange.
Even though domestic stocks are the basis of the vast majority of retirement plans, the incorporation of international dividend payers provides a significant benefit in terms of geographic diversification. This is because those dividend payers are located in different countries.
Evaluating Sector Tilts In Non-Domestic Markets
By applying a stringent dividend screen to a universe that does not include the United States, it is inevitable that a different sector distribution will be produced in comparison to domestic counterparts.
The majority of the international fund’s investments are concentrated in the energy, telecommunications, and insurance industries, which is reflective of the most profitable business models that are currently operating in other countries.
This sectoral variation is a useful addition to standard domestic portfolios because it offers exposure to cash-generating industries that frequently trade at different valuations than domestic technology and consumer discretionary sectors.
Examining Total Return Profiles And Distribution Metrics
Performance metrics demonstrate the viability of applying quality screens internationally. The fund generated a one-year total return of 22.82%, with share prices moving from $27.06 to $33.24, alongside a year-to-date gain of 13.39%.
Regarding distributions, the fund distributed $1.1083 over the trailing twelve months, with an annualized forward payout figure of $1.4284. Furthermore, the fund maintains a low expense ratio of 0.08%, aligning with Schwab low-cost indexing standards.
Understanding The Impact Of Currency Fluctuations
The translation of currencies is the primary factor that differentiates domestic performance from international returns. Because the fund invests in unhedged foreign equity, a decline in the value of the United States dollar relative to other currencies, such as the euro, the British pound, the Australian dollar, and the Japanese yen, results in a direct increase in returns that are denominated in dollars.
On the other hand, a strengthening dollar creates headwinds for the economy. When it comes to recent strong trailing returns, investors need to be aware that favorable currency translation contributed to those returns, and that this tailwind can suddenly reverse without any prior warning.
Tax Implications And Optimal Portfolio Size
The incorporation of an international dividend fund serves as the missing half of a comprehensive global income strategy. This is in contrast to the common practice of replacing domestic holdings with foreign holdings. This is due to the fact that the fund works in conjunction with domestic holdings rather than acting in opposition to them.
It is recommended that a modest 15% to 25% of a dividend sleeve be allocated to international equities. This will ensure that non-U.S. payers are captured and that a currency hedge is provided. Taking this allocation into consideration is necessary in order to guaranty profitability.
There is also the possibility that foreign withholding taxes can be reclaimed as a foreign tax credit in taxable accounts. This is an additional possibility. If, on the other hand, investors already hold broad international index funds, they should avoid duplicating their exposure. This is due to the fact that the possibility is present.
Conclusions and Investment Timeframes Worldwide
When conducting an analysis of the benefits of international dividend funds, it is essential to place a strong emphasis on the significance of expanding the range of income beyond the confines of the domestic market.
The maintenance of a balanced global allocation continues to be essential for optimizing the long-term resilience of a portfolio. This is because investors are attempting to strike a balance between the volatility of currencies and attractive foreign yields and low expense ratios.