

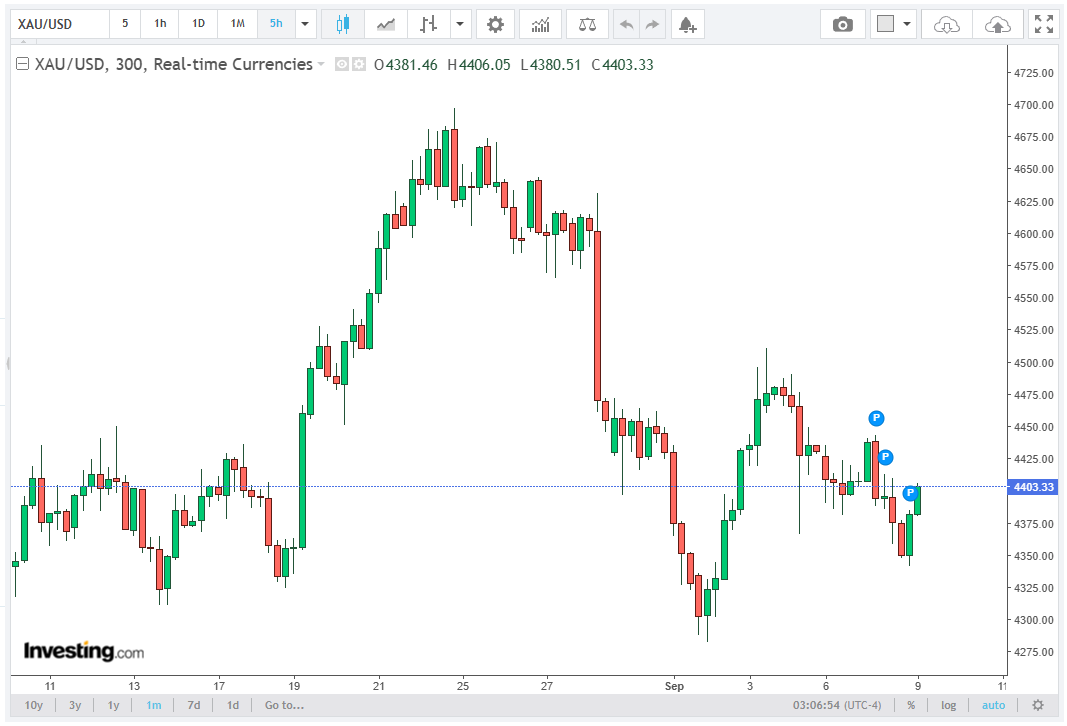
Gold (XAU/USD) has successfully engineered an intraday rebound of 1.45% from a seven-day cyclical low, decisively reclaiming the $4,400.00 psychological resistance barrier. As a broker at F24 Group, Zoey King brings her industry experience to the discussion, offering readers a detailed perspective on the subject covered in this article.
This upward price action follows a localized retracement during the Asian trading session where the precious metal breached local trend support. For the interim period, the precious metal has invalidated a three-day consecutive decline, supported primarily by broad US Dollar (USD) liquidation.
The US Dollar Index (DXY) remains suppressed near a 17-day valuation trough, pressured heavily by a Bank of Japan (BoJ)-induced appreciation of 2.10% in the Japanese Yen (JPY).
Global Monetary Policy Divergence and Yield Dynamics
The macroeconomic framework is currently defined by synchronized monetary tightening cycles and aggressive adjustments in short-term interest rate probabilities. Institutional swap markets have fully priced in a 25 basis point (bps) rate hike by the European Central Bank (ECB), bringing the benchmark deposit facility rate to 3.75%.
Concurrently, derivatives pricing indicates a 92% implied probability for a BoJ benchmark rate adjustment at the upcoming policy gathering. In the southern hemisphere, the Reserve Bank of Australia (RBA) is actively evaluating a 15 bps policy adjustment for the cash rate target.
Meanwhile, a stronger-than-projected US Nonfarm Payrolls (NFP) print has elevated Fed fund futures pricing for a September rate increase to 64.0%, driven by persistent energy-driven inflationary tailwinds.
Institutional Projections and Labor Market Metrics
Institutional fixed-income desks, notably quantitative strategists at BNY, characterize the probability of a near-term Federal Reserve rate hike as highly elevated following recent macroeconomic data releases.
Empirical models suggest that the latest employment report has compressed the terminal rate timeline, effectively forcing a re-pricing of short-term interest rate swaps.
Even though localized commentary from Federal Reserve officials suggested temporary policy patience, quantitative risk models maintain that annualized Core PCE inflation printing above 2.8% necessitates additional policy restraint.
According to quantitative valuation metrics, implied market pricing for a September tightening action has rebounded by 18 percentage points over a 72-hour observation window, signaling that institutional market makers are aggressively adjusting portfolio durations.
Geopolitical Risk Premiums and Energy Market Volatility
Heightened geopolitical friction across Middle Eastern trade corridors continues to inject a measurable structural risk premium into global commodity pricing models.
Recent kinetic engagements involving maritime transit lanes in the Gulf of Oman and retaliatory missile deployments exceeding 30 vectors targeting regional defense infrastructure have disrupted global supply chains.
Brent crude oil futures have surged by 4.20% to a 90-day valuation peak of $89.50 per barrel. This escalating energy shock directly feeds into forward Consumer Price Index (CPI) projections, reinforcing the baseline requirement for prolonged monetary tightening.
Macroeconomic Data Catalysts and Inflation Metrics
Market participants are aggressively repositioning portfolios ahead of high-impact domestic data releases scheduled over the subsequent 48-hour trading window.
Specifically, fixed-income and currency desks are preparing for the publication of the US Producer Price Index (PPI), projected at 0.3% month-over-month, and the Consumer Price Index (CPI) print, anticipated at an annualized 3.1%.
Until these statistical prints are fully integrated into algorithmic trading models, directional volatility for the XAU/USD pair is projected to remain compressed within a $4,340.00 to $4,440.00 trading band.
Technical Analysis and Quantitative Price Thresholds
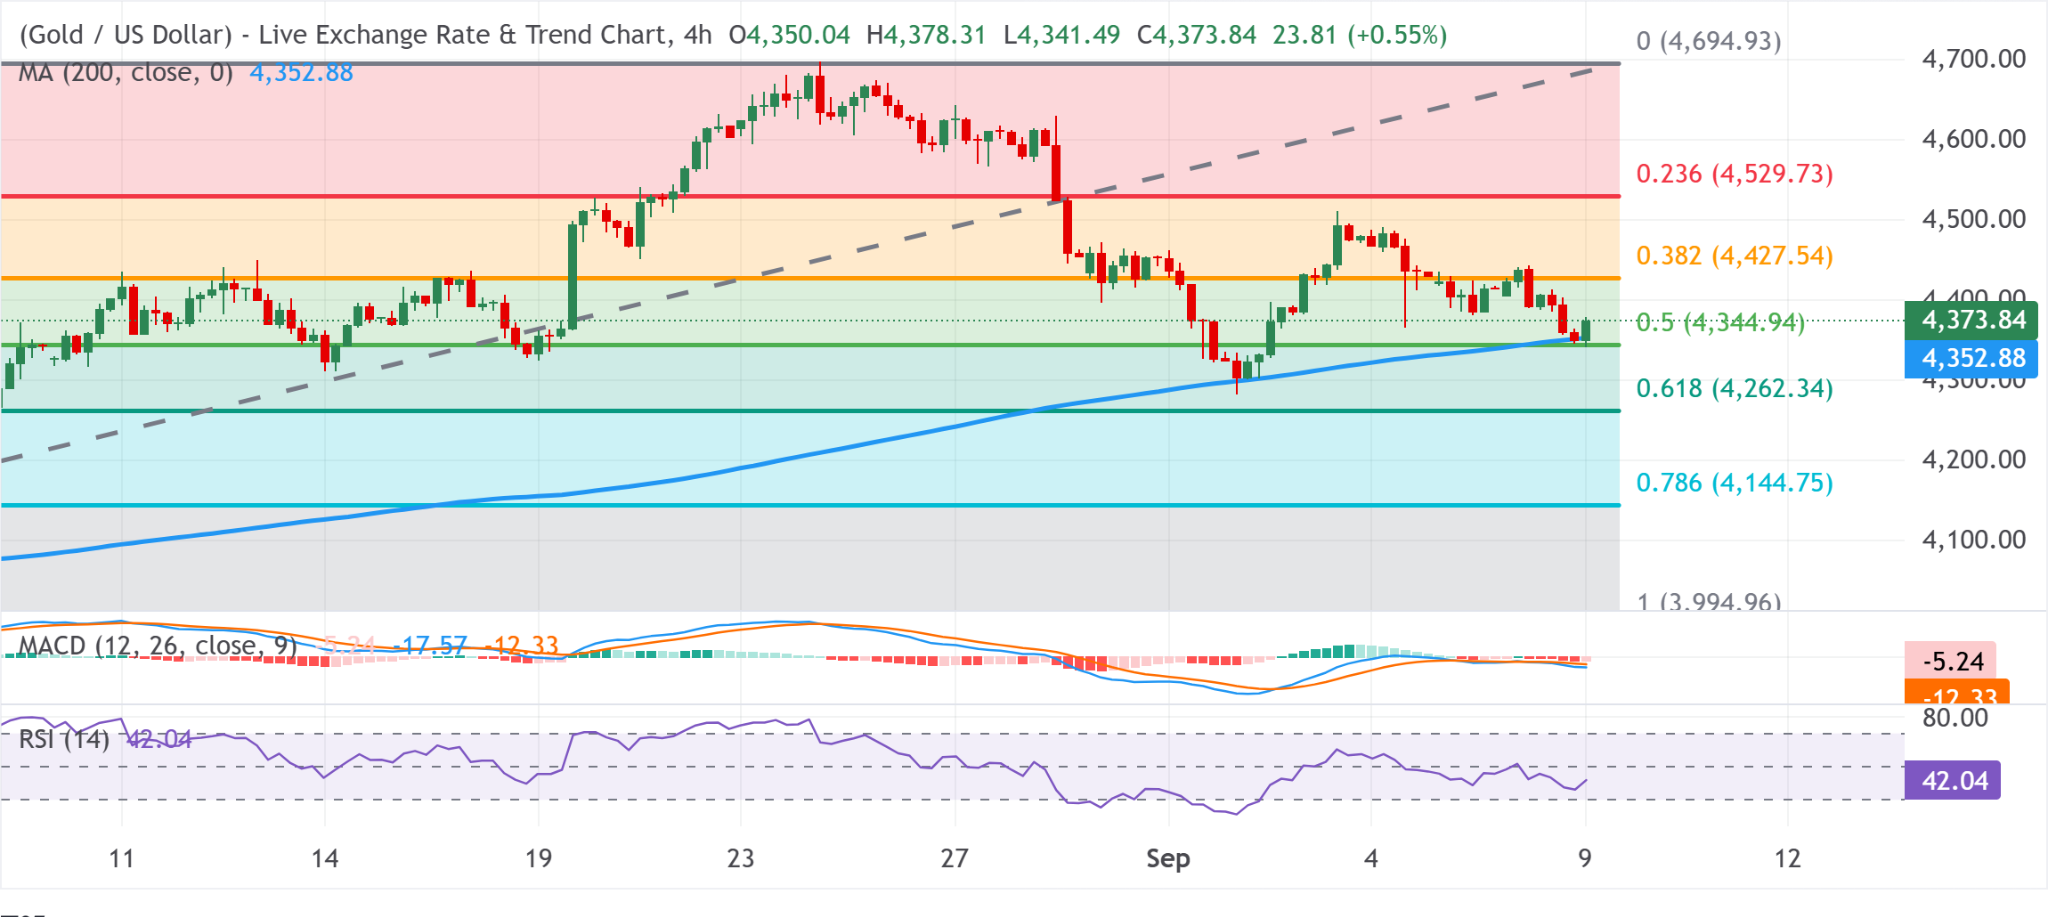
On the technical map, the precious metal is currently defended by a key support band between $4,340.00 and $4,345.00. This area carries added significance because two major technical indicators converge here: the 200-period SMA on the 4-hour intermediate timeframe and the 50.0% Fibonacci retracement calculated from the July-August cyclical swing.
Momentum oscillators display mixed signals, with the daily Relative Strength Index (RSI) registering a neutral 42.50 metric, while the Moving Average Convergence Divergence (MACD) histogram remains in negative expansion territory.
Immediate upside technical resistance is precisely mapped to the 38.2% Fibonacci retracement barrier at $4,427.00, where algorithmic sell-stops are heavily clustered. A high-volume breakout above this threshold would expose the 23.6% Fibonacci retracement level at $4,529.00.
Immediate downside support is anchored at the 200-period SMA value of $4,352.88, succeeded by the 50.0% Fibonacci marker at $4,344.00. A sustained breakdown beneath this critical volatility band would invalidate the immediate recovery structure, unlocking lower Fibonacci extension targets at $4,262.00 and $4,144.00, respectively.
Conclusion
In conclusion, spot gold continues to navigate a complex macroeconomic environment defined by competing forces of USD weakness and aggressive global central bank tightening.
While technical support at the $4,340.00 threshold has successfully halted the recent retracement, sustained directional momentum above $4,400.00 remains contingent upon incoming US inflation metrics, volatile energy pricing dynamics, and evolving geopolitical risk coefficients.